




Login to Internet banking
A brand-new experience - smarter, faster, and secured
BRAVO (Auto Sweep)
Convert the idle funds in your current account into a fixed deposit with the BRAVO feature.
Know More
Zero Forex Markup Current Account
Maximise your savings and boost profitability with our Zero Forex Markup current accounts
Know More
BRAVO (Auto Sweep)
Convert the idle funds in your current account into a fixed deposit with the BRAVO feature.
Know More
You gain a dedicated partner committed to helping you reach your full potential and achieve new heights
Know More



Enjoy Zero Forex on all IDFC FIRST Bank Credit Cards
Save more on all international spends
Know More
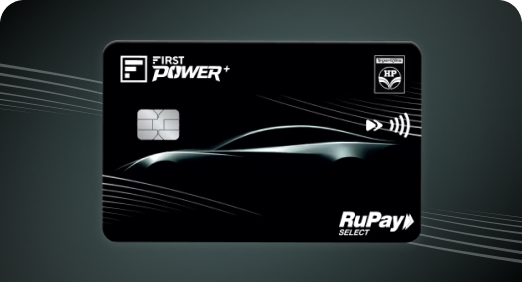
A Card that Powers your Savings & Lifestyle
IDFC FIRST Bank HPCL Credit Card

Most Searched
Earn up to 7% interest on your Savings Account
Open Account Now
Download our app
Get instant help for all your queries in one place
Unlock features, exclusively available
only on the IDFC FIRST Bank app
Trusted by 1.2+ million Indians.
4.8
4.8

Tools & Calculators
Privilege Program


Tools & Calculators
 Rental income earned in India must be credited to an NRO savings account to remain compliant with RBI regulations.
Using the correct NRI savings account helps you manage TDS, maintain proper tax records, and transfer funds abroad within permitted limits without complications.
IDFC FIRST Bank offers seamless NRI Banking services, making it easier to open and manage NRI accounts with clear compliance support and convenient access to funds.
If you earn rental income from property in India, having the right NRI savings account is essential. It enables you to receive and manage your India-based income efficiently while complying with applicable banking and FEMA regulations.
So, can an NRI have a savings account in India to manage these funds? The answer is yes but knowing which type of account is crucial. Let’s explore how the right NRI savings account can help you receive, manage, and stay compliant with your rental income in India.
An NRI account is a bank account designed specifically for NRIs to manage their income in India and abroad, in line with the Reserve Bank of India (RBI) and the Foreign Exchange Management Act (FEMA) regulations. You can maintain two primary types of NRI savings accounts in India:
An NRE savings account is designed for foreign income, which is earnings generated outside India. Money credited to an NRE account is and is tax-free in India as per current Indian tax laws. You can repatriate funds freely. So, NRE accounts are ideal for NRIs who earn abroad and want to temporarily park their savings in India.
An NRO account, by contrast, is structured for domestic income earned within India. Rental receipts, pension and income from dividends must be deposited into an NRO savings account. Funds in an NRO account remain subject to Indian tax laws, and you’ll pay applicable income tax on your income.
Rental income earned in India is classified as Indian income, regardless of where you reside. And, as per the guidelines, such income must be credited to an NRO account. If you use an NRE account for rental deposits, it is a compliance violation.
Even after selecting the right NRI savings account, many NRIs remain anxious about the finer details. Let’s address some of the most common concerns.
Yes, the NRO Savings Account is subject to taxation under Indian laws. The interest earned on your IDFC FIRST Bank NRO account is taxed at 30% plus applicable surcharge and cess. This is known as Tax Deducted at Source (TDS). However, you may seek relief under the Double Taxation Avoidance Agreement (DTAA) if your country of residence has such an agreement with India.
While NRE accounts offer free repatriation, NRO accounts allow you to repatriate up to USD 1 million per financial year, subject to applicable taxes and documentation.
Once you understand the importance of choosing the right NRI savings account, the next step is to select a banking partner that simplifies the process. This is where IDFC FIRST Bank NRI Banking Services stands out. It brings together compliance, convenience, and control in one place through the following features:
You can open your NRI savings account online with a fully digital process. Submit your details, upload KYC documents, and get started without visiting India.
With IDFC FIRST Bank, you can access personalised assistance from NRI banking experts who guide you through documentation, taxation queries, and account management.
This way, you can stay informed about TDS, repatriation rules, and regulatory requirements to keep your NRI savings account compliant at all times.
With the IDFC FIRST Mobile Banking App, you can manage your funds anytime, anywhere, with real-time tracking and easy transactions.
Transfer money within India or abroad with zero remittance processing fees and competitive exchange rates.
Easily transfer eligible funds overseas (as per RBI guidelines) with the required documentation.
In addition to handling your rental income, you can make bill payments, open deposits, or apply for a PIS through one streamlined NRI savings account platform.
Owning property in India should be a source of financial growth, not stress. By ensuring your rental income is channeled through a compliant NRI savings account, you protect yourself from regulatory scrutiny and simplify your global tax planning. With IDFC FIRST Bank NRI Banking services, you aren’t just opening an account; you are securing a partner that understands the value of your time and the importance of your Indian roots.
Open your NRI Savings Account today to experience stress-free property management!
Yes, provided domestic savings accounts are converted to NRO accounts within a reasonable period of becoming an NRI. Continuing to operate a resident savings account as an NRI violates FEMA regulations.
Yes, the interest earned on an NRO account is taxable in India. However, India has signed Double Taxation Avoidance Agreements (DTAA) with many countries, which may allow you to claim a credit for these taxes paid in India against your tax liability in your country of residence.
Yes. Many NRIs maintain both types of NRI savings accounts. There is no regulatory restriction on holding both, and in practice, this dual structure gives you greater flexibility in managing your finances across geographies.
The features, benefits and offers mentioned in the article are applicable as on the day of publication of this blog and is subject to change without notice. The contents herein are also subject to other product specific terms and conditions and any third party terms and conditions, as applicable. Please refer our website www.idfcfirst.bank.in for latest updates.