




Login to Internet banking
A brand-new experience - smarter, faster, and secured
BRAVO (Auto Sweep)
Convert the idle funds in your current account into a fixed deposit with the BRAVO feature.
Know More
Zero Forex Markup Current Account
Maximise your savings and boost profitability with our Zero Forex Markup current accounts
Know More
BRAVO (Auto Sweep)
Convert the idle funds in your current account into a fixed deposit with the BRAVO feature.
Know More
You gain a dedicated partner committed to helping you reach your full potential and achieve new heights
Know More



Enjoy Zero Forex on all IDFC FIRST Bank Credit Cards
Save more on all international spends
Know More
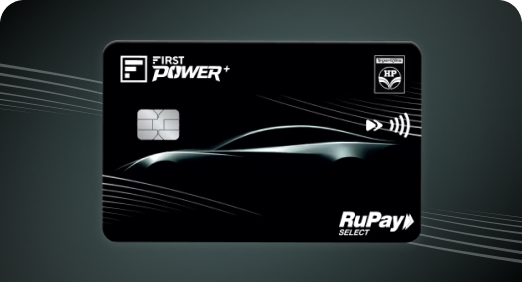
A Card that Powers your Savings & Lifestyle
IDFC FIRST Bank HPCL Credit Card

Most Searched
Earn up to 7% interest on your Savings Account
Open Account Now
Download our app
Get instant help for all your queries in one place
Unlock features, exclusively available
only on the IDFC FIRST Bank app
Trusted by 1.2+ million Indians.
4.8
4.8

Tools & Calculators
Privilege Program


Tools & Calculators
Credit Card
Summary: A secured credit card is an excellent option for people looking to build or improve their credit history. Read on to learn everything about secured credit cards in India, how it differs from an unsecured one and why you should consider them.
A credit card undoubtedly is a saviour in many situations especially in managing finances and accessing instant credit. However, most of them fall into the "unsecured" category of cards, which means you can get one without collateral. This means the card owner must have a good credit score or CIBIL score to get a credit card. But what if you don't have a credit score, have a low credit score, are a homemaker, retired, or have just begun earning? Solution - get a secured credit card!
A Secured Credit Card is a type of Credit Card that requires the cardholder to make a cash deposit upfront, which is then used as collateral against the credit limit. This can be in the form of fixed deposits as well.
Essentially, the credit limit on a Secured Credit Card is equal to the amount of the deposit, and the cardholder cannot spend more than the credit limit. This type of credit card is often used by people with limited or poor credit history, and those who are trying to rebuild their credit.
When you apply for a Secured Credit Card, you will need to provide a cash deposit or open a fixed deposit with the Credit Card Issuer. The amount of the deposit typically starts at INR 2000 and can go as high as the depositor wants in some cases. The credit card issuer holds the deposit as collateral against the credit limit, usually equal to the deposit amount.
Once the deposit has been made, you can use the Secured Credit Card in India or abroad just like any other Credit Card to make purchases, pay bills, and carry a balance from month to month. However, not every Secured Credit Card offers attractive deals and offers, which is why it is important to look for one that actually helps you save money through discounts, reward points, and other benefits.
Do remember that if you fail to make a payment on the card, the issuer can use the deposit to cover the balance. This is what makes the card "secured" i.e. the issuer has a guarantee that they will be able to recoup their losses if the cardholder fails to make payments.
There are several advantages to using a secured credit card, particularly for people trying to build or rebuild their credit. These include:
Secured Credit Cards are often easier to get than unsecured Credit Cards, even if you have a bad or no credit history. Because the card issuer has your cash deposit as collateral, they're taking on less risk by issuing you a credit card.
One of the main benefits of using a secured credit card is that it can help you build or rebuild your credit. By making on-time payments and keeping your credit utilisation low, you can show lenders that you're a responsible borrower, which can improve your credit score over time.
If you have no credit or bad credit, getting approved for loans or unsecured credit cards can be difficult. Using a Secured Credit Card responsibly establishes a positive credit history and demonstrates to lenders that you're a trustworthy borrower.
A secured credit card provides added security compared to using cash or a debit card. If your card is lost or stolen, you can report it to the issuer and not be held responsible for unauthorised charges. This protection can provide peace of mind when making purchases or travelling.
If you use your Secured Credit Card responsibly, some issuers may increase your credit limit over time. This can improve your credit utilization ratio, which is an important factor in determining your credit score.
A Secured Credit Card can be used just like any other Credit Card, which means you can use it to make purchases, pay bills, benefit from easy EMI feature, and build credit at the same time.
Not all secured credit cards offer these advantages, so it's important to research and compare different options before applying. Additionally, responsibly using your secured credit card is essential to reap these benefits fully.
A fixed deposit backed Secured Credit Card, FIRST EA₹N offers all the benefits of a RuPay Credit Card with cashback rewards.
Here are a few advantages of using the IDFC FIRST EA₹N Credit Card:
Not only this, but this Secured Credit Card also comes with welcome benefits and offers easy and convenient EMIs, balance transfer privileges, and more.
Make use of the convenient and online application process provided by IDFC FIRST Bank to apply for the FIRST EA₹N Credit Card todayand enjoy all the benefits of owning a Credit Card while building a solid credit history.
The contents of this article/infographic/picture/video are meant solely for information purposes. The contents are generic in nature and for informational purposes only. It is not a substitute for specific advice in your own circumstances. The information is subject to updation, completion, revision, verification and amendment and the same may change materially. The information is not intended for distribution or use by any person in any jurisdiction where such distribution or use would be contrary to law or regulation or would subject IDFC FIRST Bank or its affiliates to any licensing or registration requirements. IDFC FIRST Bank shall not be responsible for any direct/indirect loss or liability incurred by the reader for taking any financial decisions based on the contents and information mentioned. Please consult your financial advisor before making any financial decision.
The features, benefits and offers mentioned in the article are applicable as on the day of publication of this blog and is subject to change without notice. The contents herein are also subject to other product specific terms and conditions and any third party terms and conditions, as applicable. Please refer our website www.idfcfirst.bank.in for latest updates.