



Login to Internet banking
A brand-new experience - smarter, faster, and secured
You gain a dedicated partner committed to helping you reach your full potential and achieve new heights
Know More
BRAVO (Auto Sweep)
Convert the idle funds in your current account into a fixed deposit with the BRAVO feature.
Know More
Zero Forex Markup Current Account
Maximise your savings and boost profitability with our Zero Forex Markup current accounts
Know More


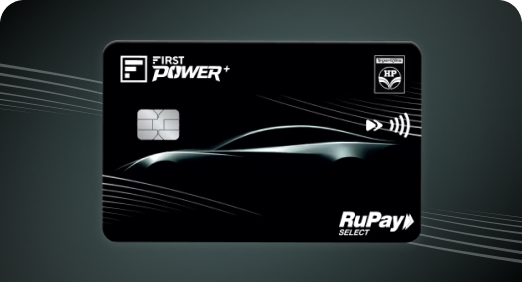
A Card that Powers your Savings & Lifestyle
IDFC FIRST Bank HPCL Credit Card

Most Searched
Earn up to 7% interest on your Savings Account
Open Account Now
Download our app
Get instant help for all your queries in one place
Unlock features, exclusively available
only on the IDFC FIRST Bank app
Trusted by 1.2+ million Indians.
4.8

4.8

Tools & Calculators
Privilege Program


Tools & Calculators

Unlock features, exclusively available
only on the IDFC FIRST Bank app
Savings Account
 Stopping your existing ELSS investments, might be an undesirable step.
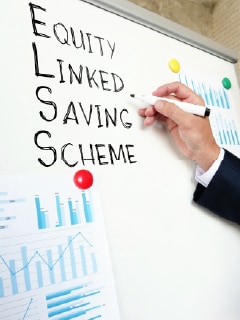
ELSS funds can help achieve your financial goals by creating an equity-linked corpus.
If you stop, you might lose out on value, depending on market volality and performance of funds of that time, and it wil have a negative imapct on your planned savings
ELSS funds have a lock-in period, before which you can not liquidate.
The Union Budget 2023 made the new tax regime all the more attractive for reducing tax liability. However, the new regime doesn’t offer tax deductions under Section 80C for ELSS (Equity Linked Saving Scheme) funds and other investments.
If you consider opting for the new tax regime when filing your taxes, you might be tempted to stop your existing ELSS investments. However, this might be an undesirable step.
Also read: https://www.idfcfirst.bank.in/finfirst-blogs/finance/difference-between-money-finance-funds
ELSS funds are equity-oriented mutual fund schemes that have the potential to generate attractive returns on your investment over time. So, your savings will be impacted if you stop investing in these funds. You would lose out on the return potential of these schemes – a loss that is not recommended.
ELSS funds have a lock-in period of 3 years. If you have invested in a lump sum, you must wait 3 years before you can redeem the fund. In the case of SIPs (Systematic Investment Plans), the lock-in period of 3 years applies to each SIP instalment. So, while you can discontinue your SIPs, you cannot liquidate the ELSS folio before the lock-in period ends.
The equity market is volatile, and when you want to redeem your ELSS investment, the market might not be conducive to your decision. If the market is falling, you might suffer a loss on redemption.
While ELSS investments offer tax benefits on investment, saving tax is not the only consideration. You may save to create a corpus for your financial goals. Such goals will be impacted if you discontinue investing.
Also read: https://www.idfcfirst.bank.in/finfirst-blogs/savings-account/how-to-set-achievable-financial-goals
Measure the tax efficiency of your decision to stop ELSS investments. Check your tax liability under the old and new tax regimes and choose where ELSS funds have the lowest tax liability. If the new tax regime is better, you can switch without stopping your ELSS funds. It would allow you to save tax, invest, earn returns, and create a corpus for your goals.
ELSS funds can help achieve your financial goals by creating an equity-linked corpus. So, don’t stop your ELSS investments, whatever tax regime you choose. If you choose the old regime, you can claim Section 80C deductions on ELSS investments and an exemption on long-term capital gains. Besides, if you open an IDFC FIRST Bank Savings Account, you can also claim a deduction on the interest earned under Section 80TTB.
So, understand the laws governing the new tax regime and make the right choice.
The contents of this article/infographic/picture/video are meant solely for information purposes. The contents are generic in nature and for informational purposes only. It is not a substitute for specific advice in your own circumstances. The information is subject to updation, completion, revision, verification and amendment and the same may change materially. The information is not intended for distribution or use by any person in any jurisdiction where such distribution or use would be contrary to law or regulation or would subject IDFC FIRST Bank or its affiliates to any licensing or registration requirements. IDFC FIRST Bank shall not be responsible for any direct/indirect loss or liability incurred by the reader for taking any financial decisions based on the contents and information mentioned. Please consult your financial advisor before making any financial decision.
The features, benefits and offers mentioned in the article are applicable as on the day of publication of this blog and is subject to change without notice. The contents herein are also subject to other product specific terms and conditions and any third party terms and conditions, as applicable. Please refer our website www.idfcfirst.bank.in for latest updates.


You will earn