



Login to Internet banking
A brand-new experience - smarter, faster, and secured
BRAVO (Auto Sweep)
Convert the idle funds in your current account into a fixed deposit with the BRAVO feature.
Know More
Zero Forex Markup Current Account
Maximise your savings and boost profitability with our Zero Forex Markup current accounts
Know More
BRAVO (Auto Sweep)
Convert the idle funds in your current account into a fixed deposit with the BRAVO feature.
Know More
You gain a dedicated partner committed to helping you reach your full potential and achieve new heights
Know More



Enjoy Zero Forex on all IDFC FIRST Bank Credit Cards
Save more on all international spends
Know More
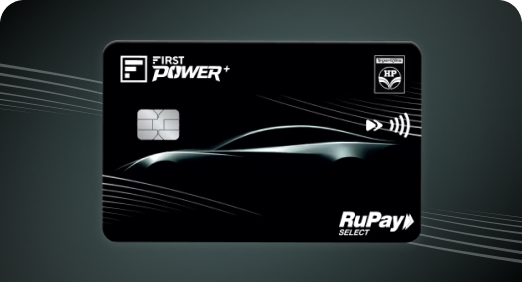
A Card that Powers your Savings & Lifestyle
IDFC FIRST Bank HPCL Credit Card

Most Searched
Earn up to 7% interest on your Savings Account
Open Account Now
Download our app
Get instant help for all your queries in one place
Unlock features, exclusively available
only on the IDFC FIRST Bank app
Trusted by 1.2+ million Indians.
4.8

4.8

Tools & Calculators
Privilege Program


Tools & Calculators

ECLGS 5.0 helps eligible businesses and MSMEs access additional working capital through participating lenders. Backed by a Government of India guarantee, the scheme enables easier credit access, supports cash flow management, and offers collateral-free funding for eligible MSMEs.
The Emergency Credit Line Guarantee Scheme 5.0 is a government-backed credit guarantee programme designed to provide additional credit support to businesses facing liquidity constraints due to economic disruptions arising from the West Asia crisis.
ECLGS 5.0 helps businesses access additional working capital by providing government-backed guarantee support to lenders. With a large portion of the lending risk covered, banks can offer credit more confidently, making it easier for eligible businesses to secure funding for their day-to-day operations, manage cash flow needs and continue pursuing growth opportunities.
The scheme is administered by the National Credit Guarantee Trustee Company Limited (NCGTC) under the Department of Financial Services, Ministry of Finance.
For eligible enterprises, ECLGS 5.0 functions as a specialised working capital support scheme, enabling them to secure additional funding while benefiting from favourable terms and reduced costs.
Businesses exploring a business loan government scheme India can consider ECLGS 5.0 as a potential funding avenue, subject to eligibility and lender assessment.
Read more

One of the biggest advantages of the scheme is the guaranteed support provided by the government.
• MSMEs receive up to 100% guarantee coverage on the amount in default.
• Non-MSMEs and eligible airline sector borrowers receive 90% guarantee coverage.
This reduces lending risk and improves access to credit.

During uncertain business conditions, access to timely funding makes all the difference. ECLGS 5.0 helps eligible businesses secure additional working capital to keep operations running smoothly.
One of the practical benefits of ECLGS 5.0 is that businesses do not have to pay any guarantee fees. By removing this additional cost, the scheme helps keep borrowing more affordable, allowing businesses to direct their funds towards everyday operations, growth plans and other business priorities.

Participating lenders are not permitted to charge processing fees for loans sanctioned under ECLGS 5.0, making it more cost-effective for eligible borrowers.

Businesses can prepay the loan without any prepayment charges.
For MSMEs and Non-MSMEs, the scheme offers:
• Loan tenure of up to 5 years
• Moratorium period of 1 year from the date of first disbursement.
• Competitive interest rates
For affordable borrowing conditions, ECLGS 5.0 has capped interest rates. For MSMEs, the interest rate is linked to the bank’s External Benchmark Lending Rate (EBLR). This helps in keeping financing costs transparent and competitive.
Following conditions need to be met to qualify under ECLGS 5.0.
The scheme is available for:
MSMEs
Non-MSMEs
Scheduled Passenger Airline Sector borrowers
The borrower’s credit facilities should be classified as “Standard” and should not fall under SMA-2 status as on 31 March 2026 across all lenders.
ECLGS 5.0 is intended for existing borrowers on the books of participating lending institutions as of 31 March 2026. New borrowers are not eligible under the scheme.
MSME applicants are generally required to possess a valid UDYAM Registration or Udyam Assist Certificate (UAC) to establish their MSME status under the scheme.
Applications must be submitted through lenders that are onboarded on the JanSamarth portal and participating under the scheme.
The amount of assistance available under ECLGS 5.0 depends on the borrower’s outstanding working capital exposure during Q4 FY26.
Eligible borrowers can avail:
• Up to 20% of the peak fund-based working capital outstanding during the period from 01 January 2026 to 31 March 2026
• Maximum assistance of ₹100 crore per borrower across all Member Lending Institutions (MLIs)
The eligible facilities considered for determining peak working capital utilisation may include:
• Cash Credit (CC)
• Overdraft (OD)
• Working Capital Demand Loan (WCDL)
• Working Capital Term Loan (WCTL)
Let’s say a manufacturing MSME had a peak working capital utilisation of ₹10 crore between January and March 2026. In such a case, the business may be able to access an additional credit facility of up to ₹2 crore under ECLGS 5.0. Of course, the actual amount approved will depend on the lender’s evaluation and the applicable scheme conditions.
This makes the scheme particularly valuable as an MSME government loan scheme for businesses seeking additional liquidity without arranging fresh collateral.
ECLGS 5.0 may be suitable for:
For businesses dealing with short-term liquidity challenges, ECLGS 5.0 can provide the extra financial cushion needed to keep operations running smoothly.
Enterprises with healthy repayment records that require incremental funding for inventory, operations or business continuity may find the scheme useful.

Since no fresh collateral is generally required for MSME and Non-MSME borrowers under the scheme, it serves as an effective source of collateral-free MSME funding.


The aim of ECLGS 5.0 is to provide eligible businesses with easier access to funding. Approval of funds depends on borrower’s eligibility, lender’s evaluation and the applicable scheme guidelines. Factors such as interest rates, repayment terms, and documentation can vary by lender. Businesses should connect with their lender to understand the specific applicable terms. The information provided here is for general guidance only. Since scheme guidelines may change over time, applicants should check the latest updates and consult their lender for detailed eligibility criteria, applicable terms and the most current information before applying.