



Login to Internet banking
A brand-new experience - smarter, faster, and secured
BRAVO (Auto Sweep)
Convert the idle funds in your current account into a fixed deposit with the BRAVO feature.
Know More
Zero Forex Markup Current Account
Maximise your savings and boost profitability with our Zero Forex Markup current accounts
Know More
BRAVO (Auto Sweep)
Convert the idle funds in your current account into a fixed deposit with the BRAVO feature.
Know More
You gain a dedicated partner committed to helping you reach your full potential and achieve new heights
Know More



Enjoy Zero Forex on all IDFC FIRST Bank Credit Cards
Save more on all international spends
Know More
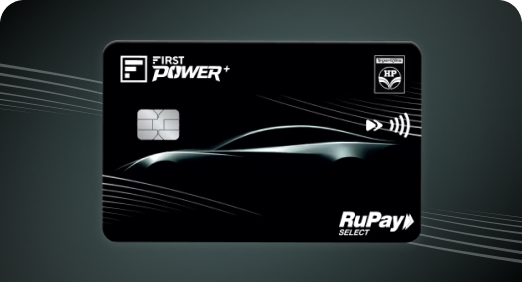
A Card that Powers your Savings & Lifestyle
IDFC FIRST Bank HPCL Credit Card

Most Searched
Earn up to 7% interest on your Savings Account
Open Account Now
Download our app
Get instant help for all your queries in one place
Unlock features, exclusively available
only on the IDFC FIRST Bank app
Trusted by 1.2+ million Indians.
4.8

4.8

Tools & Calculators
Privilege Program


Tools & Calculators

Unlock features, exclusively available
only on the IDFC FIRST Bank app
Personal Loan
 You can take a second personal loan, but approval depends on your income, repayment capacity, and credit history.
Approaching your existing lender often works better, as you may get favorable terms based on your repayment track record.
Handling multiple loans responsibly can strengthen your credit score, but defaults or delays can harm your creditworthiness.
A top-up loan could be a smarter alternative to a second personal loan, offering extra funds without the hassle of applying with a new lender.
At times, a single loan may not be enough to meet personal needs and you may require a second one. Here are answers to some questions you should know out before applying for a second loan.
A second personal loan is an additional unsecured loan you take while an existing personal loan is still active. You can apply for it from your current lender or a different financial institution. However, approval is not automatic. The lender will assess your income, existing EMIs, credit score, repayment history, employment or business stability, and overall debt obligations before deciding your eligibility.
Since you will have to manage another repayment obligation, it is important to ensure that the combined EMIs remain affordable within your monthly budget. Taking a second loan without assessing your repayment capacity can increase your debt burden and put pressure on your finances.
Approaching a different lender for the second loan can seem like a smart move. However, it won’t help your approval chances if:
Both - your existing lender as well as your new lender, will look at your repayment capacity and income to determine your eligibility for a second loan.
A second personal loan may be considered when you need additional funds, and your existing loan does not adequately cover the requirement.
Some common reasons include:
Managing an urgent expense: You may require additional funds for an unexpected medical expense, emergency, or other immediate financial requirement.
Funding a major personal need: A second loan can help finance expenses such as home improvements, education, travel, or a family event.
Avoiding disruption to existing finances: If you have an ongoing loan with a fixed repayment schedule, an additional loan can provide separate funds without altering the existing loan arrangement.
Meeting a temporary funding gap: If your income and repayment capacity support another EMI, a second loan can help bridge a short-term financial requirement.
Before applying, compare the interest rate, processing fees, tenure, EMI, and total repayment cost. Most importantly, calculate the combined EMI of all your loans against your monthly income.
Approaching your existing lender with a new financial requirement is usually recommended. You get to negotiate better terms based on your repayment history and credit score. You may also get to borrow funds as per your needs at competitive personal loan interest rates.
Managing multiple loans responsibly can positively impact credit scores by demonstrating a history of timely repayments. However, defaulting on multiple loans can adversely affect creditworthiness.
A top-up loan can be an alternative to taking a separate personal loan, particularly if your existing lender offers this facility.
The key differences are:
| Factor | Second Personal Loan | Top-Up Loan |
Loan arrangement |
A separate loan with a new repayment schedule |
Additional borrowing linked to an existing loan, subject to lender policy |
Application |
Usually requires a fresh loan application and eligibility assessment |
May involve a simpler process for eligible existing borrowers |
Lender |
Can be taken from an existing or new lender |
Generally offered by the existing lender |
Repayment |
Requires managing another loan and the EMI payments |
Repayment structure depends on the lender's top-up terms |
Eligibility |
Based on income, credit profile, existing liabilities, and lender criteria |
Based on factors such as repayment history, income, outstanding loan, and lender policy |
Best suited for |
Borrowers who need additional funds and meet eligibility for another loan |
Existing borrowers who need additional funds and qualify for a top-up |
The number of personal loans an individual can have depends on various factors, including their financial situation, creditworthiness, and lender policies. However, borrowing responsibly is crucial to avoid over-leverage and financial strain.
A top-up is a provision that lets you add a certain amount to your existing home loan amount. With top-up loans, you don’t need to approach another lender for the second loan. Some lenders will also let you combine your previous loan with the top-up loan or treat them both as separate loans. The value of your top-up loan entirely depends on your eligibility. The lender will take into account factors such as your credit score, current liabilities, and income before approving the loan.
Before deciding whether to take a second loan, carefully analyze the factors that affect your eligibility to ensure you make the right choice. If you're considering a Personal Loan balance transfer, you can easily apply for one online at your convenience.
Yes, you can apply for another personal loan if your repayment history is good and your income allows an additional EMI. FIRSTmoney also offers multiple on-demand loans from your approved loan offer without the need to reapply from scratch.
Yes, you can have two personal loans simultaneously, subject to the lender’s eligibility criteria. Your income, existing EMIs, credit score, repayment history and overall repayment capacity are generally considered before approval.
Applying for another loan may result in a hard enquiry, which can temporarily affect your credit score. However, making timely EMI payments on both loans can help maintain a healthy credit profile.
A top-up loan can be a convenient alternative if your existing lender offers it and you meet the eligibility criteria. It may involve a simpler application process since the lender already has your loan and repayment details.
Yes, you can apply to another lender. However, changing lenders does not remove the need to demonstrate sufficient income and repayment capacity. The new lender will also consider your existing loan obligations before making a decision.
Disclaimer
The contents of this article/infographic/picture/video are meant solely for information purposes. The contents are generic in nature and for informational purposes only. It is not a substitute for specific advice in your own circumstances. The information is subject to updation, completion, revision, verification and amendment and the same may change materially. The information is not intended for distribution or use by any person in any jurisdiction where such distribution or use would be contrary to law or regulation or would subject IDFC FIRST Bank or its affiliates to any licensing or registration requirements. IDFC FIRST Bank shall not be responsible for any direct/indirect loss or liability incurred by the reader for taking any financial decisions based on the contents and information mentioned. Please consult your financial advisor before making any financial decision.
The features, benefits and offers mentioned in the article are applicable as on the day of publication of this blog and is subject to change without notice. The contents herein are also subject to other product specific terms and conditions and any third party terms and conditions, as applicable. Please refer our website www.idfcfirst.bank.in for latest updates.