



Login to Internet banking
A brand-new experience - smarter, faster, and secured
BRAVO (Auto Sweep)
Convert the idle funds in your current account into a fixed deposit with the BRAVO feature.
Know More
Zero Forex Markup Current Account
Maximise your savings and boost profitability with our Zero Forex Markup current accounts
Know More
BRAVO (Auto Sweep)
Convert the idle funds in your current account into a fixed deposit with the BRAVO feature.
Know More
You gain a dedicated partner committed to helping you reach your full potential and achieve new heights
Know More



Enjoy Zero Forex on all IDFC FIRST Bank Credit Cards
Save more on all international spends
Know More
A Card that Powers your Savings & Lifestyle
IDFC FIRST Bank HPCL Credit Card

Most Searched
Earn up to 7% interest on your Savings Account
Open Account Now
Download our app
Get instant help for all your queries in one place
Unlock features, exclusively available
only on the IDFC FIRST Bank app
Trusted by 1.2+ million Indians.
4.8

4.8

Tools & Calculators
Privilege Program


Tools & Calculators
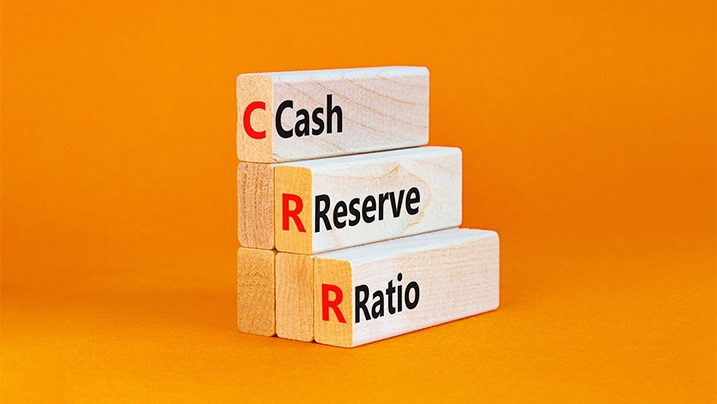
Economies are usually volatile. They fluctuate depending on several internal and external factors. Banks and their ability to lend money are especially susceptible to these factors. Proper regulation and financial management can help avoid bumps in banking operations and maintain enough liquidity. The Reserve Bank of India (RBI) uses Cash Reserve Ratio (CRR) to eliminate such risks and regulate the money supply in the market. CRR impacts banks and financial institutions in how they offer loans and other credit products.
The cash reserve is the amount of capital a bank has. The Cash Reserve Ratio (CRR) is the percentage of total deposits a bank must have in cash to operate risk-free. The Reserve Bank of India decides the amount and is kept with them for financial security. The bank cannot use this amount for lending and investment purposes and does not get any interest from the RBI. CRR applies to scheduled commercial banks, while the regional rural banks and NBFCs are excluded.
Let us use an example to understand CRR further. Assuming the CCR is 6%, a bank must deposit ₹6 for every ₹100 raised in deposits. Technically, the cash reserves for a scheduled commercial bank must not fall below 6% of the total net demand and time liabilities (NDTL) that the bank holds on a fortnight basis. Earlier, CRR ranged from 3% to 20%; however, there is no upper or lower limit now.
Following are the critical objectives of the Cash Reserve Ratio.
While the CRR affects how banks offer loans, you can count on IDFC FIRST Bank to help you whenever you need financial help. The bank provides convenient loans through online and offline channels, offering a hassle-free application process and minimal documentation. You can opt for up to a personal loan of ₹1 crore at competitive interest rates starting at 10.49%.
The Cash Reserve Ratio (CRR) ensures consumers' financial security. It forces banks to maintain adequate liquidity.
The Cash Reserve Ratio directly impacts the level of liquidity in the country's economy. You can assume it is a money supply valve RBI holds to control inflation. In case of higher inflation, the RBI can increase the Cash Reserve Ratio requirements to reduce the banks' lending capacity, thereby lowering inflation.
The Cash Reserve Ratio is calculated based on the bank's net demand and time liabilities (NDTL). Net demand and time liability can be defined as the total deposits of the bank with the public or other banks minus the deposits of other banks. Liabilities such as current deposits, cash certificates, demand drafts, fixed deposits (FDs), gold deposits, dividends etc., constitute NDTL. Here is a simple expression to calculate the cash reserve ratio:
CRR = (Liquid Cash/NDTL) * 100
The RBI keeps changing the cash reserve ratio for consumers' safety and a smooth economy. It ensures that the banks have adequate funds to meet customers' requirements even during high withdrawals. Moreover, RBI can also increase or decrease the CRR to meet its other requirements, such as supplying money to boost the economy.
Knowing how CRR works for banks and financial institutions can help you make informed decisions and choose when to go for a suitable financial product. The Cash Reserve Ratio is a safety net for the customers and is an integral part of RBI's monetary policies.
Disclaimer
The contents of this article/infographic/picture/video are meant solely for information purposes. The contents are generic in nature and for informational purposes only. It is not a substitute for specific advice in your own circumstances. The information is subject to updation, completion, revision, verification and amendment and the same may change materially. The information is not intended for distribution or use by any person in any jurisdiction where such distribution or use would be contrary to law or regulation or would subject IDFC FIRST Bank or its affiliates to any licensing or registration requirements. IDFC FIRST Bank shall not be responsible for any direct/indirect loss or liability incurred by the reader for taking any financial decisions based on the contents and information mentioned. Please consult your financial advisor before making any financial decision.
The features, benefits and offers mentioned in the article are applicable as on the day of publication of this blog and is subject to change without notice. The contents herein are also subject to other product specific terms and conditions and any third party terms and conditions, as applicable. Please refer our website www.idfcfirst.bank.in for latest updates.