



Login to Internet banking
A brand-new experience - smarter, faster, and secured
BRAVO (Auto Sweep)
Convert the idle funds in your current account into a fixed deposit with the BRAVO feature.
Know More
Zero Forex Markup Current Account
Maximise your savings and boost profitability with our Zero Forex Markup current accounts
Know More
BRAVO (Auto Sweep)
Convert the idle funds in your current account into a fixed deposit with the BRAVO feature.
Know More
You gain a dedicated partner committed to helping you reach your full potential and achieve new heights
Know More



Enjoy Zero Forex on all IDFC FIRST Bank Credit Cards
Save more on all international spends
Know More
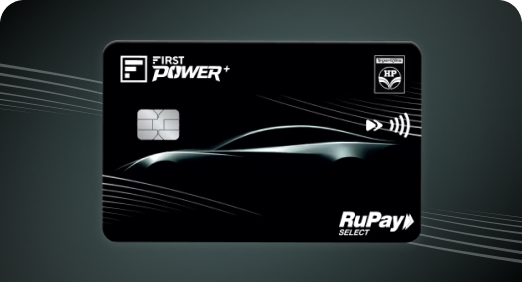
A Card that Powers your Savings & Lifestyle
IDFC FIRST Bank HPCL Credit Card

Most Searched
Earn up to 7% interest on your Savings Account
Open Account Now
Download our app
Get instant help for all your queries in one place
Unlock features, exclusively available
only on the IDFC FIRST Bank app
Trusted by 1.2+ million Indians.
4.8

4.8

Tools & Calculators
Privilege Program


Tools & Calculators

Unlock features, exclusively available
only on the IDFC FIRST Bank app
Personal Loan
 Switching a personal loan is worth it when the interest you save is more than the cost of switching.
Check whether interest is calculated on a flat or reducing balance, as it changes your real cost even at the same quoted rate.
Compare the interest left on your current loan with the total interest on the new offer, not just the two EMIs.
Add up foreclosure charges on your current loan and the processing fee on the new one before you decide.
A personal loan balance transfer or switching lenders is worth it when the new offer saves you more than it costs to switch. A low quoted interest rate is just one part of that. This guide shows what to compare between your existing loan and the new offer.
Two personal loans with the same interest rate can still cost different. It depends on how interest is calculated, so keep this in mind for any personal loan interest rate comparison:
Point of comparison |
Flat rate |
Reducing balance |
Interest is calculated on |
The original loan amount, for the full tenure |
The outstanding balance after each EMI |
Interest component over time |
Stays the same every month |
Reduces with every EMI |
Cost to you |
Higher for the same quoted rate |
Lower for the same quoted rate |
For example, on ₹5 lakh over 5 years, a 10% flat rate means about ₹2.5 lakh in interest, while a 10% reducing rate means about ₹1.37 lakh. FIRSTmoney personal loan uses the reducing-balance method to calculate interest on your loan.
Start with what is left to pay on your current loan, not what you originally borrowed.
Outstanding principal: Ask your current lender for a foreclosure statement. This is the amount the new loan has to cover.
Remaining interest: Compare the interest still due on your current loan with the total interest on the new offer for the same outstanding amount.
Repayment stage: On a reducing-balance loan, most of the interest is paid in the early EMIs. The later you switch, the smaller the saving.
EMI and tenure: A longer tenure lowers the EMI but adds interest. Use an EMI calculator to compare both loans over the same remaining tenure.
Your current lender: Ask whether they can lower your interest rate before you switch. It may save you the switching costs altogether.
Say you took a ₹5 lakh loan at 14% p.a. for 5 years and have paid 12 EMIs. A new lender offers 11% p.a. on the outstanding amount for the remaining 4 years.
Parameter |
Current loan |
New offer |
Interest rate |
14% p.a. |
11% p.a. |
Outstanding amount |
₹4,25,746 |
₹4,25,746 |
Remaining tenure |
48 months |
48 months |
EMI |
₹11,634 |
₹11,004 |
Interest still to pay |
₹1,32,692 |
₹1,02,428 |
The lower interest rate saves you about ₹30,264 in interest. Now subtract the switching costs:
Foreclosure charge on the current loan, assuming 4% plus GST: about ₹20,095.
Processing fee on the new loan, assuming 2% including GST: about ₹8,515.
That leaves a net saving of just ₹1,654. If the new loan carries zero processing fee, the net saving rises to about ₹10,169. If your current loan has no foreclosure charge, the saving is higher still.
Figures are illustrative, calculated on a reducing balance basis. Actual rates and charges depend on your lenders and loan terms.
Check these on both loans. Ask each lender for the full schedule of charges, or read the Key Fact Statement (KFS), which shows the annual percentage rate (APR) including interest and fees.
Foreclosure charges: Your current lender may charge a percentage of the outstanding amount, plus GST, to close the loan early. Some loans also have a lock-in period. FIRSTmoney carries zero foreclosure charges and no lock-in period.
Processing fee: A one-time fee on the new loan. On FIRSTmoney, there’s zero processing fee on all loan amounts during the current limited-time offer.
Stamp duty: Charged on the loan agreement as per your state's Stamp Act.
Overdue EMI and bounce charges: Applied if an EMI is missed or a payment fails. Keep your current EMIs running until the old loan is closed.
Service charges: Fees for physical statements, duplicate documents or other service requests.
Switching works only when the interest you save is higher than all these charges combined.
Aspect |
Ask yourself |
Interest rate and method |
Is the new interest rate lower, and is it on a reducing balance? |
Total cost |
Is the APR on the new KFS lower than your current loan's? |
Switching charges |
Do the foreclosure and processing costs eat up your saving? |
Tenure and EMI |
Does the new EMI fit your monthly budget? |
Flexibility and servicing |
Can you foreclose without charges and manage the loan digitally? |
Switch when the new loan costs less overall, not just when the advertised interest rate is lower. Compare the calculation method, the interest left on your current loan, and every charge on both sides. Switching or personal loan balance transfer early in the tenure, to a reducing-balance loan with low switching costs, usually saves the most.
A new loan application also adds a hard enquiry to your credit report, so avoid applying with several lenders at once.
Not necessarily. Besides the low interest rate, compare the new tenure, other applicable charges, and services, and total repayment to pick a better deal for switching loans.
Check processing, stamping, foreclosure, EMI bounce, overdue-payment, and service-related charges.
There is no fixed difference. Compare the interest savings with all applicable charges to see if switching pays off.
It can, briefly. The new application adds a hard enquiry, and a new loan account appears on your report. Closing the old loan on time and paying the new EMIs regularly helps your score recover.
The contents of this article/infographic/picture/video are meant solely for information purposes. The contents are generic in nature and for informational purposes only. It is not a substitute for specific advice in your own circumstances. The information is subject to updation, completion, revision, verification and amendment and the same may change materially. The information is not intended for distribution or use by any person in any jurisdiction where such distribution or use would be contrary to law or regulation or would subject IDFC FIRST Bank or its affiliates to any licensing or registration requirements. IDFC FIRST Bank shall not be responsible for any direct/indirect loss or liability incurred by the reader for taking any financial decisions based on the contents and information mentioned. Please consult your financial advisor before making any financial decision.
The features, benefits and offers mentioned in the article are applicable as on the day of publication of this blog and is subject to change without notice. The contents herein are also subject to other product specific terms and conditions and any third party terms and conditions, as applicable. Please refer our website www.idfcfirst.bank.in for latest updates.