



Login to Internet banking
A brand-new experience - smarter, faster, and secured
BRAVO (Auto Sweep)
Convert the idle funds in your current account into a fixed deposit with the BRAVO feature.
Know More
Zero Forex Markup Current Account
Maximise your savings and boost profitability with our Zero Forex Markup current accounts
Know More
BRAVO (Auto Sweep)
Convert the idle funds in your current account into a fixed deposit with the BRAVO feature.
Know More
You gain a dedicated partner committed to helping you reach your full potential and achieve new heights
Know More



Enjoy Zero Forex on all IDFC FIRST Bank Credit Cards
Save more on all international spends
Know More
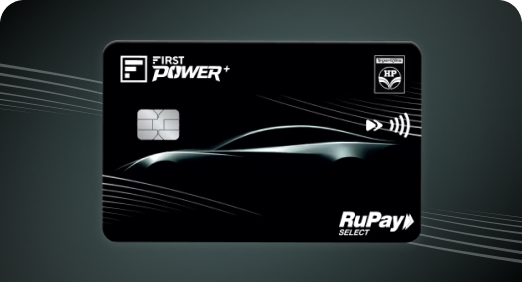
A Card that Powers your Savings & Lifestyle
IDFC FIRST Bank HPCL Credit Card

Most Searched
Earn up to 7% interest on your Savings Account
Open Account Now
Download our app
Get instant help for all your queries in one place
Unlock features, exclusively available
only on the IDFC FIRST Bank app
Trusted by 1.2+ million Indians.
4.8

4.8

Tools & Calculators
Privilege Program


Tools & Calculators

Unlock features, exclusively available
only on the IDFC FIRST Bank app
Personal Loan
 Loan insurance provides financial protection by paying outstanding loan instalments in the event of death, disability, or a loss of employment.
It is useful for long-term loans such as home loans.
Borrowers should compare the cost of insurance premiums against the actual risk before purchasing loan insurance.
Loans have become an essential part of fulfilling dreams. It can be owning a home, buying a car, or pursuing higher education but with borrowing comes a significant responsibility - its repayment. Life is unpredictable, and unforeseen events like job loss, illness, disability, or even death can affect a borrower's ability to repay the loan. This is where loan insurance steps in as a crucial financial safety net. In this article, know all about loan insurance, its types and more.
Loan insurance is financial protection that covers borrowers against sudden life events like death, disability, or loss of employment. If the borrower is unable to repay the loan due to such events, the policy pays the outstanding balance, and therefore, the family is not responsible for the burden of loan repayment. Buying loan insurance is optional, but majority of lenders suggest it as a layer of extra protection.
If a borrower takes a instant loan, they can choose loan insurance by paying a premium in advance or by paying the premium in instalments along with the Equated Monthly Instalments (EMIs) of their loan. In case of an insured incident, like a serious illness or accident resulting in disability, the insurance company pays the outstanding loan amount.
When purchasing loan insurance, borrowers usually choose between a single premium and a regular premium payment method. Here is how the two compare:
Aspect |
Single premium |
Regular premium |
Payment structure |
Entire insurance cost paid upfront as a lump sum |
Cost spread out and paid at fixed intervals alongside EMIs |
Impact on loan amount |
Often added to the loan amount, increasing the total loan disbursed |
Loan amount stays lower since the premium is not added upfront |
Interest impact |
Avoids extra interest building up on the premium over the loan tenure |
Can work out costlier over the full tenure due to added interest on each instalment |
Cash flow requirement |
Suited to borrowers who can afford a larger upfront payment |
Suited to borrowers who prefer smaller, manageable monthly outflows |
Monthly EMI |
Not affected by the premium once the loan is disbursed |
Slightly higher each month, as the premium is added to the instalment |
It is worth asking the lender for a cost comparison between both options before deciding, factoring in the loan tenure, interest rate, and comfort with an added monthly cost.
Loan insurance policies vary depending on the loan type and coverage. Some of these are:
While loan insurance is not mandatory, it still provides peace of mind, particularly for long-term loans like home loans that need to be paid off over decades. Insurance is not always required for less-than-a-decade credits like personal loans since they are unsecured and generally have more manageable repayment terms.
Financial security isn’t just about savings – it’s also about making informed borrowing decisions.
FIRSTmoney provides a risk-free and hassle-free borrowing experience for those who need quick funds without the extra cost of loan insurance. With loan amounts between ₹ 50,000 and ₹ 15 lakhs, borrowers can avail loans without collateral or mandatory insurance policies.
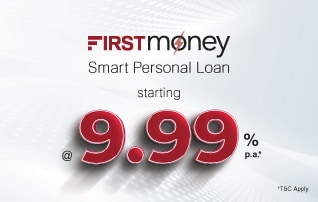
They can select their repayment schedules between 9 to 60 months based on their ability to pay EMIs. The low personal loan interest rate of 9.99% p.a. and an end-to-end digital application process help in quick approvals and disbursals within 10 minutes. Moreover, there are no foreclosure charges so borrowers can repay early without any additional fee. Check your personal Loan eligibility now!
Loan insurance may be an important safeguard in the case of long-term and high-value loans. Yet in short-term money requirements, an easy lending service such as a smart personal loan can turn out to be better.
Refer to the EMI calculator to calculate EMIs for your next car, two-wheeler, home loan, etc.
Loan insurance is an optional protection policy linked to a loan. It is designed to cover outstanding dues when specific insured events happen, as defined in the policy. Typical covers include death, permanent disability, critical illness, or job loss, subject to inclusions, exclusions, and claim conditions. If a valid claim is approved, the insurer settles eligible amounts with the lender. Review benefits, waiting periods, claim process, and costs before deciding.
Whether to buy loan insurance depends on the product and your comfort with risk. Some offers present it as an add on, while others may not include it. Consider your dependants, existing insurance, emergency reserves, and job stability. Read the Key Fact Statement and policy brochure to see coverage, exclusions, cost, and cancellation timelines. You can compare third party covers too. Choose what fits your budget and overall protection plan.
Protection works through claims. If a covered event occurs and the insurer accepts the claim, the insurer pays eligible amounts toward the loan as per terms. That can reduce or clear dues, easing pressure on household cash flow. It may also help avoid missed EMIs while matters are resolved. Outcomes depend on coverage type, sums insured, exclusions, waiting periods, and documentation. Keep copies of policy, premium receipts, and contact details.
Requirements can vary by product and time. Some journeys may present insurance as an option, while others may not display it. To confirm the current position for your application, check the Key Fact Statement, MITC, and the offer screen in the app. Ask whether acceptance is optional and whether alternatives exist. Always review benefits, exclusions, premium, and cancellation rules before you decide. Request written clarification if anything feels unclear today.
Cost depends on cover amount, borrower age, tenure, loan size, insurer underwriting, and taxes. Pricing is usually shown as a one-time premium or as financed premium added to the loan. Review the illustration alongside your offer to see total premium, GST, and any interest if financed. Compare scope of cover, not only price. Check renewal rules if the tenure exceeds policy duration, and keep the premium receipt securely somewhere.
Policy contracts specify cooling off or free look periods and later cancellation rules. During the free look window, you can usually review terms and ask for cancellation as per insurer process. After that, refunds and surrender values depend on policy type and elapsed time. Check who the policyholder is, whether premium was financed, and how refunds are credited. Always read the insurer’s document and keep acknowledgements for your records carefully.
The contents of this article/infographic/picture/video are meant solely for information purposes. The contents are generic in nature and for informational purposes only. It is not a substitute for specific advice in your own circumstances. The information is subject to updation, completion, revision, verification and amendment and the same may change materially. The information is not intended for distribution or use by any person in any jurisdiction where such distribution or use would be contrary to law or regulation or would subject IDFC FIRST Bank or its affiliates to any licensing or registration requirements. IDFC FIRST Bank shall not be responsible for any direct/indirect loss or liability incurred by the reader for taking any financial decisions based on the contents and information mentioned. Please consult your financial advisor before making any financial decision.
The features, benefits and offers mentioned in the article are applicable as on the day of publication of this blog and is subject to change without notice. The contents herein are also subject to other product specific terms and conditions and any third party terms and conditions, as applicable. Please refer our website www.idfcfirst.bank.in for latest updates.


Check the latest rates.

Know your total loan cost.

Estimate your EMI instantly.

Compare EMIs for multiple loan types.

See why your score matters.