



Login to Internet banking
A brand-new experience - smarter, faster, and secured
BRAVO (Auto Sweep)
Convert the idle funds in your current account into a fixed deposit with the BRAVO feature.
Know More
Zero Forex Markup Current Account
Maximise your savings and boost profitability with our Zero Forex Markup current accounts
Know More
BRAVO (Auto Sweep)
Convert the idle funds in your current account into a fixed deposit with the BRAVO feature.
Know More
You gain a dedicated partner committed to helping you reach your full potential and achieve new heights
Know More



Enjoy Zero Forex on all IDFC FIRST Bank Credit Cards
Save more on all international spends
Know More
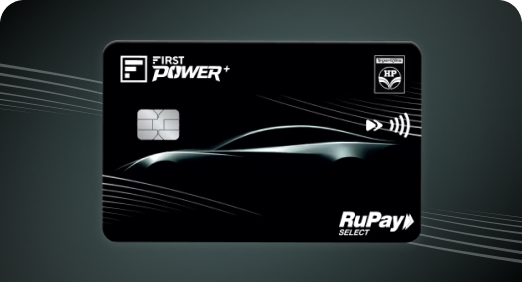
A Card that Powers your Savings & Lifestyle
IDFC FIRST Bank HPCL Credit Card

Most Searched
Earn up to 7% interest on your Savings Account
Open Account Now
Download our app
Get instant help for all your queries in one place
Unlock features, exclusively available
only on the IDFC FIRST Bank app
Trusted by 1.2+ million Indians.
4.8

4.8

Tools & Calculators
Privilege Program


Tools & Calculators
 Corporate fixed deposits are offered by companies and non-bank financial firms and carry higher interest rates compared to bank FDs.
These deposits offer flexible tenures from a few months to several years and have options for monthly, quarterly, or maturity-based interest payouts.
Before investing you should check the issuer’s credit rating, financial stability and claim settlement record for safety.
Keeping your deposits diversified and limiting exposure to any single company helps manage risk.
Corporate fixed deposits (FDs), also known as company fixed deposits, are a type of term deposit offered by non-banking financial companies (NBFCs), housing finance companies, and corporates to raise debt capital. They are similar to traditional bank fixed deposits but offer relatively higher interest rates.
A corporate FD is an investment product offered by non-banking finance companies and firms to raise funds from the public. In a corporate FD, the investor invests a lumpsum amount with the company for a predefined tenure, ranging from a few months to a fixed number of years . The company offers a fixed rate of interest on the investment for the entire tenure. The principal and interest earned are repaid at the time of maturity.
● Corporate deposits are issued by non-banking finance companies, firms, and corporates. They are not issued by commercial banks.
● Mature in a predefined period ranging from a few months to a fixed number of years.
● Offer guaranteed returns in the form of fixed interest rates.
● Corporate FD rates are higher than bank fixed deposits.
● Interest is payable monthly, quarterly, annually, or at maturity.
● Principal and interest repaid at the time of maturity.
● Available in cumulative and non-cumulative options.
● Minimum investment amount varies across issuers.
● Corporate FDs can be pledged as collateral to get loans.
● Premature withdrawals are allowed at a penalty in some cases.
● Interest earned is fully taxable as per the investor's tax slab.
● Individuals - Resident Indians as well as NRIs can invest in corporate fixed deposits.
● HUFs - Hindu Undivided Families are also permitted to invest in these instruments.
● Partnership firms, companies, trusts, and societies can also purchase company FDs.
● Minors can invest in corporate FDs via guardians.
● Financial institutions, NBFCs and banks can invest their surplus funds in corporate FDs.
Thus, corporate fixed deposits are suitable for a wide range of individual and institutional investors looking for relatively higher and stable returns.
Let's look at some of the major benefits of corporate fixed deposits.
● Higher interest rates - The interest rates offered on corporate FDs are usually about 1-3% higher than bank FDs. This allows investors to earn greater returns on savings.
● Flexible tenures - Corporate deposits offer tenure options ranging from a few months to a fixed number of years. [JV1] Investors can pick a suitable tenure as per their requirements.
● Regular income - Corporate FDs offer periodic payouts of interest - monthly, quarterly, half-yearly, or annually. This provides investors with a regular income stream.
● Capital safety - Corporate deposits are relatively safe if invested in high-rated companies. They offer guaranteed returns of principal and interest.
● Liquidity - Investors can take premature withdrawals, subject to certain rules and conditions, incurring a penalty.[JV2] Also, investors can take loans against their FDs.
● Simplicity and transparency - The process of investing in corporate FDs is quite straightforward. The terms and returns are clearly specified.
Corporate FDs present an attractive investment option for those seeking higher returns with varied tenure options to meet different financial goals.
Here is a step-by-step process to evaluate and choose a suitable corporate fixed deposit.
● Check company reputation - The issuer company must have a strong reputation, financial stability, sound creditworthiness, and be registered with RBI.
● Research credit ratings - Only invest in companies rated highly by CRISIL, ICRA, and CARE with ratings like AAA or equivalent.
● Compare interest rates - Compare FD rates across issuers and tenures to find the highest rate based on your investment horizon.
● Understand all terms - Read the terms carefully to know the lock-in rules, interest payout frequency, premature withdrawal rules, etc.
● Check claim settlement history - Review the claim settlement ratio and track record in repaying deposits on time.
● Limit exposure - Do not invest more than 15-20% of your portfolio in a single company's FDs.
By evaluating these parameters, you can zero in on a safe and optimal corporate FD investment.
Conclusion
Corporate fixed deposits offer the benefit of higher interest rates as compared to bank FD[JV1] s, making them attractive fixed income instruments. However, the risks are also higher due to a lack of insurance coverage. By considering factors like company reputation, financials, credit ratings and claim history, investors can make informed investment decisions. Investing a small portion of one's portfolio in highly rated corporate FDs can provide good returns. However, investments must be spread across companies and tenures to minimise risk. Thus, Corporate FDs present a rewarding investment option for certain types of investors willing to take on additional risk for higher returns.
The contents of this article/infographic/picture/video are meant solely for information purposes. The contents are generic in nature and for informational purposes only. It is not a substitute for specific advice in your own circumstances. The information is subject to updation, completion, revision, verification and amendment and the same may change materially. The information is not intended for distribution or use by any person in any jurisdiction where such distribution or use would be contrary to law or regulation or would subject IDFC FIRST Bank or its affiliates to any licensing or registration requirements. IDFC FIRST Bank shall not be responsible for any direct/indirect loss or liability incurred by the reader for taking any financial decisions based on the contents and information mentioned. Please consult your financial advisor before making any financial decision.
The features, benefits and offers mentioned in the article are applicable as on the day of publication of this blog and is subject to change without notice. The contents herein are also subject to other product specific terms and conditions and any third party terms and conditions, as applicable. Please refer our website www.idfcfirst.bank.in for latest updates.