



Login to Internet banking
A brand-new experience - smarter, faster, and secured
You gain a dedicated partner committed to helping you reach your full potential and achieve new heights
Know More
BRAVO (Auto Sweep)
Convert the idle funds in your current account into a fixed deposit with the BRAVO feature.
Know More
Zero Forex Markup Current Account
Maximise your savings and boost profitability with our Zero Forex Markup current accounts
Know More



Enjoy Zero Forex on all IDFC FIRST Bank Credit Cards
Save more on all international spends
Know More
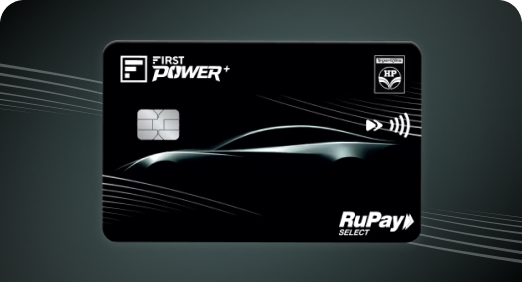
A Card that Powers your Savings & Lifestyle
IDFC FIRST Bank HPCL Credit Card

Most Searched
Earn up to 7% interest on your Savings Account
Open Account Now
Download our app
Get instant help for all your queries in one place
Unlock features, exclusively available
only on the IDFC FIRST Bank app
Trusted by 1.2+ million Indians.
4.8

4.8

Tools & Calculators
Privilege Program


Tools & Calculators

Unlock features, exclusively available
only on the IDFC FIRST Bank app
Personal Loan
 A loan agreement is a legally binding document that outlines the terms and conditions between a lender and a borrower.
It specifies important details such as the loan amount, interest rate, repayment schedule, fees, and obligations of both parties.
Carefully reviewing a loan agreement before signing can help borrowers understand their financial commitments and avoid future disputes.
Different types of loans, including personal loans, home loans, and vehicle loans, are typically governed by loan agreements.
A loan agreement is one of the most important documents in the borrowing process. It defines the terms of the loan and sets clear expectations for both the lender and the borrower. While many borrowers focus primarily on the loan amount and interest rate, understanding the loan agreement is equally important. The agreement outlines the rights and responsibilities of both parties and provides clarity on how the loan will be managed throughout its tenure.
A loan agreement is a legal contract between a lender and a borrower that defines the terms under which a loan is provided and repaid. It serves as an official record of the borrowing arrangement and helps protect the interests of both parties. For digital-first loans such as FIRSTmoney, borrowers can also access and download relevant loan documents anytime through the Bank app. The agreement typically specifies details such as:
Loan amount sanctioned
Interest rate applicable
Repayment tenure
EMI schedule
Applicable fees and charges
Rights and obligations of the lender and borrower
Conditions related to default or non-payment
By signing the agreement, both parties acknowledge and agree to follow the stated terms and conditions.
A loan agreement provides clarity and accountability throughout the borrowing journey.
The agreement clearly outlines when repayments are due, how much must be paid, and the duration of the repayment period.
Important information such as interest rates, charges, and repayment terms is documented, helping borrowers understand the true cost of borrowing.
The agreement establishes legal protection for both the lender and the borrower by documenting agreed-upon terms.
Since expectations are laid out clearly, there is less room for confusion regarding responsibilities and obligations.
A loan agreement can look technical at first, but it becomes easier to understand when each component is broken down into simple terms. The following sections usually form the core of the agreement and explain what the borrower and lender are agreeing to.
This section records the borrower’s personal, contact, and identification details. It helps establish who is responsible for repaying the loan and ensures the agreement is linked to the correct individual or entity.
The loan amount shows the total sum sanctioned by the lender. Reviewing this detail helps borrowers confirm that the approved amount matches what they applied for and planned to borrow.
The interest rate explains how much the lender will charge on the borrowed amount. Since it directly affects the total repayment cost, this is one of the most important parts of the agreement to read carefully.
The repayment tenure is the period within which the loan must be repaid. It usually influences both the EMI amount and the total interest payable over the course of the loan. With personal loans such as FIRSTmoney, borrowers can choose flexible repayment tenures based on their loan amount and repayment comfort.
The EMI schedule lays out the repayment amount, due date, and payment frequency. It helps borrowers plan their monthly finances and avoid missing repayment deadlines. A personal loan EMI calculator can also help borrowers estimate repayments in advance and understand how different loan amounts or tenures may affect their monthly outflow.
This part covers costs such as processing fees, late payment charges, prepayment charges, foreclosure charges, or any other applicable fees. Reading this section helps borrowers understand the total cost of taking the loan. FIRSTmoney offers zero foreclosure charges, which gives borrowers more flexibility if they choose to close the loan before the end of the tenure.
Default terms explain what may happen if repayments are delayed or missed. This may include penalties, additional charges, or an impact on the borrower’s ability to access credit in the future.
This section defines the responsibilities of both the lender and the borrower throughout the loan period. It sets expectations clearly, so both parties understand what they are required to follow under the agreement.
Loan agreements often use financial terms that may seem technical at first. Looking at them as simple questions can make the document easier to read and understand before signing.
The interest rate is the percentage charged by the lender on the borrowed amount. For unsecured loans like an instant personal loan, it is a key factor to check because it helps determine the overall cost of the loan.
EMI stands for Equated Monthly Instalment. It is the fixed amount you repay every month and usually includes both the principal amount and the interest component. To estimate monthly repayments in advance, borrowers can use a personal loan EMI calculator for unsecured loans.
Loan tenure is the period within which the loan must be repaid. A longer tenure may reduce the EMI amount but increase the total interest paid, while a shorter tenure may increase the monthly repayment but reduce the overall interest cost.
A processing fee is a one-time charge that may be applied for processing the loan application. It is usually charged against the borrowed amount and may be deducted from the sanctioned loan amount.
Default means failing to repay the loan according to the agreed repayment schedule. This may lead to late payment charges, affect credit history, and make future borrowing more difficult.
Understanding these terms can help borrowers read the agreement more confidently and evaluate their repayment commitments with greater clarity.
A well-understood loan agreement is the foundation of responsible borrowing and confident financial decision-making.
Before signing a loan agreement, it is advisable to review the document carefully.
Pay particular attention to:
Interest rates and repayment obligations
Loan tenure and EMI amount
Processing fees and other charges
Late payment provisions
Foreclosure or prepayment conditions
Rights and responsibilities mentioned in the agreement
Terms related to missed repayments or default
Before finalising a loan, borrowers may also use a Personal Loan EMI Calculator to estimate monthly repayments and assess affordability based on the loan amount, tenure and interest rate.
Loan agreements contain obligations that both parties are expected to follow.
For borrowers, failure to meet repayment commitments may result in:
Late payment charges
Negative impact on credit history
Additional financial liabilities
Challenges in obtaining future credit
Reviewing the agreement thoroughly before signing can help prevent avoidable issues later.
A loan agreement forms the foundation of any borrowing arrangement. Understanding the loan amount, repayment terms, interest rate, applicable charges, and borrower obligations can help you make informed financial decisions with greater confidence. Those using FIRSTmoney personal loan can access all the important loan documents through the IDFC FIRST Bank Mobile Banking App.
A loan agreement is a legal document that records the terms agreed between a lender and a borrower. It explains important details such as the loan amount, interest rate, repayment schedule, fees, and the responsibilities of both parties.
Common mistakes include not checking the interest rate, missing hidden or additional charges, overlooking repayment dates, ignoring prepayment or foreclosure conditions, and signing without reading the default terms carefully.
Digital first banks like IDFC FIRST Bank, usually ask for basic personal details such as PAN and Aadhaar numbers, employment information, original PAN card for video KYC when applying for a personal loan. The exact requirements may vary based on the lender’s eligibility criteria and the borrower’s profile.
The contents of this article/infographic/picture/video are meant solely for information purposes. The contents are generic in nature and for informational purposes only. It is not a substitute for specific advice in your own circumstances. The information is subject to updation, completion, revision, verification and amendment and the same may change materially. The information is not intended for distribution or use by any person in any jurisdiction where such distribution or use would be contrary to law or regulation or would subject IDFC FIRST Bank or its affiliates to any licensing or registration requirements. IDFC FIRST Bank shall not be responsible for any direct/indirect loss or liability incurred by the reader for taking any financial decisions based on the contents and information mentioned. Please consult your financial advisor before making any financial decision.
The features, benefits and offers mentioned in the article are applicable as on the day of publication of this blog and is subject to change without notice. The contents herein are also subject to other product specific terms and conditions and any third party terms and conditions, as applicable. Please refer our website www.idfcfirst.bank.in for latest updates.