



Login to Internet banking
A brand-new experience - smarter, faster, and secured
You gain a dedicated partner committed to helping you reach your full potential and achieve new heights
Know More
BRAVO (Auto Sweep)
Convert the idle funds in your current account into a fixed deposit with the BRAVO feature.
Know More
Zero Forex Markup Current Account
Maximise your savings and boost profitability with our Zero Forex Markup current accounts
Know More



Enjoy Zero Forex on all IDFC FIRST Bank Credit Cards
Save more on all international spends
Know More
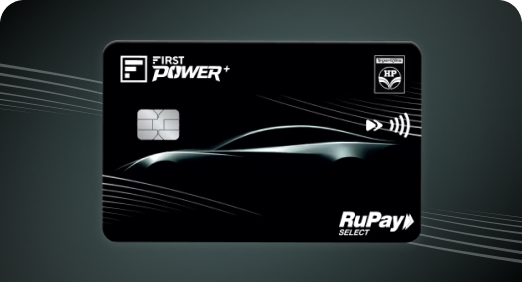
A Card that Powers your Savings & Lifestyle
IDFC FIRST Bank HPCL Credit Card

Most Searched
Earn up to 7% interest on your Savings Account
Open Account Now
Download our app
Get instant help for all your queries in one place
Unlock features, exclusively available
only on the IDFC FIRST Bank app
Trusted by 1.2+ million Indians.
4.8

4.8

Tools & Calculators
Privilege Program


Tools & Calculators

Unlock features, exclusively available
only on the IDFC FIRST Bank app
Personal Loan
 A home loan covers a portion of the property cost, while the registration, stamp duty, interior design, down payment, and moving costs come out of your pocket.
Costs other than the property value are considered discretionary under a home loan.
A FIRSTmoney personal loan helps fund costs not covered under a home loan through quick funding, flexible on-demand loans, convenient repayment, and a digital application process.
While planning the purchase of your dream home, several cost components are at play. Besides the property price, you also want to think of registration, stamp duty, interiors, and the down payment contribution. Planning for all potential expenses helps you prepare for what's ahead practically. A home loan alone may not be sufficient to cover everything. This is where a personal loan comes in handy. Explore how this home interior loan bridges the financial gap.
A home loan covers a significant part of the property's cost, but several expenses still need to be paid out-of-pocket. They include:
The property registration fee is applicable to record and legalise your home ownership. It is usually 1-2% of your property's value.
The government levies tax on the property purchase in the form of stamp duty, which varies by state. It is, like the registration fee, charged as a percentage of the property cost.
The cost of painting, furniture, fittings, repairs, and other development work can increase your spending after possession. A FIRSTmoney personal loan for home interior helps fund these varied expenses.
The sanctioned home loan typically covers 80-85% of the property value. The remaining 15-20% is your contribution in the form of a down payment.
Transporting belongings from your old home and buying essential household items can add another round of expenses that are not accounted for in a home loan.
LTV sets a limit on how much a lender can finance against the value of your property. It is structured as follows, which doesn't cover other costs:
The LTV is calculated against the property's assessed value. It determines the portion of the property cost that the lender is willing to finance through a home loan.
Expenses such as home loan stamp duty and registration charges arise from completing the property purchase. They are not part of the property value. Hence, they aren't considered under the LTV.
The choices you make with the interiors, furnishing, moving, legal advice, etc., depend on your personal requirements. Since they can differ from one buyer to another, they aren't included in the property-linked LTV calculation. A home interior loan works better for funding these expenses.
When the additional costs of owning a home stretch beyond your available savings, a personal loan offers financial support with the following benefits:
Flexible funding: You can use the funds borrowed for home renovation, legal expenses, down payment, and more without any end-use restriction.
Quick disbursal: You receive funds directly in your bank account within 10 minutes after approval with FIRSTmoney personal loan.
Convenient repayment: Choose a flexible tenure within the range of 9 to 60 months and repay in manageable EMIs.
Multiple on-demand loans: You can borrow multiple times from the approved and available FIRSTmoney loan offer as expenses arise without reapplying from scratch.
Simple application: Apply digitally with basic details and video KYC once you meet the eligibility criteria.
Based on a property value of ₹50 lakh, here's how the upfront cost would look, which a home interior loan can help you with:
Cost component |
Indicative amount |
Property value |
₹50 lakh |
Home loan (80% LTV) |
₹40 lakh |
Down payment |
₹10 lakh |
Stamp duty |
₹2-4 lakh |
Registration (0.5-2%) |
₹25,000-₹1 lakh |
Interiors & furnishing |
₹4 –₹10 lakh |
Brokerage (1-2%, if applicable) |
₹50,000-₹1 lakh |
Moving & initial setup |
₹25,000 to ₹50,000 |
Suppose you take a personal loan for ₹10 lakh with a tenure of 24 months and an interest rate of 9.99%. The resulting EMI is ₹46,140, and the total interest is ₹1,07,360.
Making a significant financial commitment like buying a home comes with a range of expenses. Considering them holistically helps to avoid surprises. Hence, as you take out a home loan, consider the additional funds you'll need for costs not covered under the LTV. Once you have a figure, you can consider a personal loan according to your needs and repayment comfort.
No, these are transaction-related expenses, not included in the property cost used to calculate home loan LTV.
Yes, you can take a home interior design loan right after you've bought a house, once you have rounded up the expenses.
The stamp duty and registration charges for a home loan vary by state and the property value. Typically, they add up to 5 to 10% of the total cost of the property.
The contents of this article/infographic/picture/video are meant solely for information purposes. The contents are generic in nature and for informational purposes only. It is not a substitute for specific advice in your own circumstances. The information is subject to updation, completion, revision, verification and amendment and the same may change materially. The information is not intended for distribution or use by any person in any jurisdiction where such distribution or use would be contrary to law or regulation or would subject IDFC FIRST Bank or its affiliates to any licensing or registration requirements. IDFC FIRST Bank shall not be responsible for any direct/indirect loss or liability incurred by the reader for taking any financial decisions based on the contents and information mentioned. Please consult your financial advisor before making any financial decision.
The features, benefits and offers mentioned in the article are applicable as on the day of publication of this blog and is subject to change without notice. The contents herein are also subject to other product specific terms and conditions and any third party terms and conditions, as applicable. Please refer our website www.idfcfirst.bank.in for latest updates.