



Login to Internet banking
A brand-new experience - smarter, faster, and secured
You gain a dedicated partner committed to helping you reach your full potential and achieve new heights
Know More
BRAVO (Auto Sweep)
Convert the idle funds in your current account into a fixed deposit with the BRAVO feature.
Know More
Zero Forex Markup Current Account
Maximise your savings and boost profitability with our Zero Forex Markup current accounts
Know More



Enjoy Zero Forex on all IDFC FIRST Bank Credit Cards
Save more on all international spends
Know More
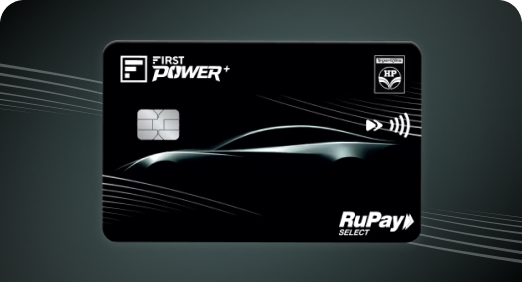
A Card that Powers your Savings & Lifestyle
IDFC FIRST Bank HPCL Credit Card

Most Searched
Earn up to 7% interest on your Savings Account
Open Account Now
Download our app
Get instant help for all your queries in one place
Unlock features, exclusively available
only on the IDFC FIRST Bank app
Trusted by 1.2+ million Indians.
4.8

4.8

Tools & Calculators
Privilege Program


Tools & Calculators

Unlock features, exclusively available
only on the IDFC FIRST Bank app
Personal Loan
 A higher down payment means a lower borrowing amount, hence lower EMI and vice versa.
Personal loan and car loan lenders are concerned with your repayment ability and existing obligations, while the dealer cares about on-time payment to process the sale.
Consider the cost of running two EMIs when taking a personal loan for a car down payment, and alternatives include your savings, zero-DP schemes, and a higher car loan LTV.
A vehicle purchase, even with a car loan, involves upfront costs such as the down payment and registration costs. Contributing more towards the purchase amount reduces the interest cost on the car loan. But if you have insufficient savings, you may have to hold out for a while. You can avoid this wait time and ease the financial pressure with a personal loan. Read ahead to learn how you can use a personal loan for a down payment.
The car loan down payment you make directly affects how much you need to borrow, thereby affecting the car loan EMI and interest. Here's a clearer overview of what to expect:
When you make a larger upfront contribution towards the purchase amount, your borrowing amount is reduced. As a result, you have a lower amount to repay, which leads to a lower monthly EMI.
Since interest is calculated on the outstanding loan amount, borrowing less by contributing more toward the down payment reduces the applicable interest. The lesser the borrowing amount, the lower the interest cost and vice versa.
When you opt for a down payment, your lender and the vehicle dealer look at the arrangement in the following way:
What matters |
Personal loan lender |
Car loan lender |
Vehicle dealer |
Repayment ability |
Looks at your age, income, employment, credit profile, and existing obligations to assess your repayment ability. |
Considers your overall repayment capacity for the principal after excluding the down payment. |
Concerned with the car loan applicable to the remaining purchase amount for the sale to proceed. |
Additional borrowing |
Assesses the personal loan as a separate unsecured borrowing |
May consider the personal loan as an existing obligation when assessing your overall debt-to-income ratio |
The additional borrowing doesn't affect how the car deal is closed |
Overall debt |
Considers whether the personal loan fits your existing financial commitments |
Needs to assess whether adding the car loan alongside a personal loan remains manageable |
Checks if the transaction can be completed as agreed as a result of the evaluation by loan providers. |
While a personal loan can reduce the stress involved in arranging for downpayment funds, it also creates a second repayment to manage. It helps to consider the combined monthly outgo before applying.
The reality of taking a personal loan for a car loan down payment includes:
Two separate obligations: You'll repay the personal loan and car loan EMIs as applicable. Your total monthly commitment is the sum of both EMIs, including other obligations.
Interest: Compare the total interest across both loans and how they affect your finances in the long run to make an informed choice.
If taking on two loans feels like too much, you have a few other ways to arrange the down payment for the vehicle purchase:
Use your available corpus to contribute toward the car loan amount. Just ensure you retain enough for other immediate needs and your financial goals.
If you do not want to worry about arranging a down payment, you may consider using a personal loan to finance the vehicle purchase. Since the loan is not tied to a specific vehicle's loan-to-value (LTV) ratio, it also gives you the flexibility to purchase a new or second-hand vehicle, subject to your eligibility and the loan amount. However, compare the applicable interest rate, EMI and total borrowing cost before opting for this route.
You can opt for IDFC FIRST Bank FIRSTmoney personal loans. It offers flexible tenures from 9 to 60 months, loan amounts from ₹50,000 to ₹15 lakh and zero foreclosure charges if you want to close your loan early.
Using a personal loan can help you purchase a vehicle without worrying about arranging a large down payment upfront. It also gives you greater flexibility to choose the vehicle you want, including a new or second-hand car, since the loan is not tied to a specific vehicle purchase. Consider the overall cost of the combined EMIs and whether another option could work better before applying for the loan.
Once you're sure, you can submit your application online with IDFC FIRST Bank’s FIRSTmoney personal loans and get funds within 10 minutes.
You will typically need to contribute 10-20% of the car's on-road price as a down payment on a car loan in India.
Yes, a higher down payment means you borrow less, which generally lowers the EMI on a car loan.
Yes, it can be a good idea to bridge the funding gap if you can comfortably handle personal loan EMIs along with a car loan.
The contents of this article/infographic/picture/video are meant solely for information purposes. The contents are generic in nature and for informational purposes only. It is not a substitute for specific advice in your own circumstances. The information is subject to updation, completion, revision, verification and amendment and the same may change materially. The information is not intended for distribution or use by any person in any jurisdiction where such distribution or use would be contrary to law or regulation or would subject IDFC FIRST Bank or its affiliates to any licensing or registration requirements. IDFC FIRST Bank shall not be responsible for any direct/indirect loss or liability incurred by the reader for taking any financial decisions based on the contents and information mentioned. Please consult your financial advisor before making any financial decision.
The features, benefits and offers mentioned in the article are applicable as on the day of publication of this blog and is subject to change without notice. The contents herein are also subject to other product specific terms and conditions and any third party terms and conditions, as applicable. Please refer our website www.idfcfirst.bank.in for latest updates.