




Login to Internet banking
A brand-new experience - smarter, faster, and secured
BRAVO (Auto Sweep)
Convert the idle funds in your current account into a fixed deposit with the BRAVO feature.
Know More
Zero Forex Markup Current Account
Maximise your savings and boost profitability with our Zero Forex Markup current accounts
Know More
BRAVO (Auto Sweep)
Convert the idle funds in your current account into a fixed deposit with the BRAVO feature.
Know More
You gain a dedicated partner committed to helping you reach your full potential and achieve new heights
Know More



Enjoy Zero Forex on all IDFC FIRST Bank Credit Cards
Save more on all international spends
Know More
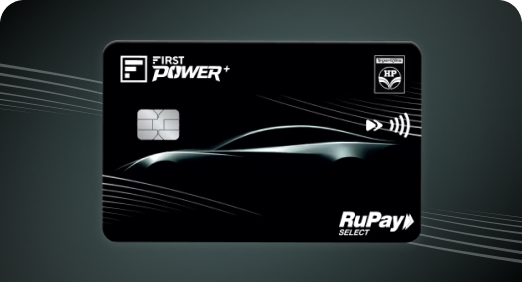
A Card that Powers your Savings & Lifestyle
IDFC FIRST Bank HPCL Credit Card

Most Searched
Earn up to 7% interest on your Savings Account
Open Account Now
Download our app
Get instant help for all your queries in one place
Unlock features, exclusively available
only on the IDFC FIRST Bank app
Trusted by 1.2+ million Indians.
4.8
4.8

Tools & Calculators
Privilege Program


Tools & Calculators
Credit Card
 RuPay credit cards can be linked to supported UPI apps, making them convenient for everyday digital payments.
These networks can be preferable for frequent international travellers, while RuPay has a stronger domestic focus.
Joining fees, annual charges, forex markup, rewards, lounge access, and other benefits vary by card and issuer, not just network.
RuPay, Visa, and Mastercard support multiple security measures. Choose a card based on your spending habits, payment needs, travel frequency, fees, and benefits.
Credit cards have become an integral part of our financial portfolio. Most major banks, including IDFC FIRST Bank, issue credit cards affiliated with payment networks such as RuPay, Visa and Mastercard.
A payment network is the system that facilitates communication between the cardholder, merchant and card issuer when a card is used for a transaction. It helps process and authorise payments, while also supporting features such as security and transaction management.
While the basic role is similar across networks, there can be differences in acceptance, benefits and features that customers should consider when applying for a new credit card.
RuPay cards, India’s answer to a global payment network, offer a plethora of benefits designed to cater to the diverse needs of Indian consumers. With features like enhanced security, affordable joining or annual fees, and cashback rewards on various transactions, RuPay cards represent a significant stride in India’s financial inclusion journey. Additionally, benefits like fuel surcharge waivers and domestic lounge access enhance the travel experience.
The IDFC FIRST Digital RuPay Credit Card offers the key benefits of RuPay Credit Cards along with additional features. Cardholders can enjoy rewards and cashback on spends such as online shopping and utility bill payments, making it a useful option for everyday spending.
RuPay Credit Cards offer faster transactions when linked to UPI, with no hidden charges. Enhanced safety through UPI PINs reduces fraud risk. Using your RuPay card for UPI transactions combines convenience, security, and savings!
Visa, the global leader in digital payments, partners with IDFC FIRST Bank to offer a suite of credit cards designed for discerning customers. The FIRST Select Credit Card, FIRST Wealth Credit Card, and FIRST WOW! Credit Card are some of the Visa-branded offerings that combine the convenience of worldwide electronic payments with exclusive benefits.
Each card is crafted to cater to different lifestyle needs, providing a range of credit limits and privileges. With Visa’s extensive network, cardholders can enjoy seamless transactions in over 200+ countries, supported by the reliability of over 150 million daily transactions.
Through their ongoing partnership, Mastercard and IDFC FIRST Bank offer a lineup of credit cards tailored for today’s lifestyles. Whether you are a frequent flyer looking for travel rewards or a savvy shopper seeking everyday value, these cards provide a flexible range of features built to match your specific spending habits.
Operating in 210+ countries, Mastercard enables a staggering 2.5 billion transactions per day, making every payment effortless and secure for IDFC FIRST Bank customers.
RuPay credit cards are issued by many public sector and private banks. Foreign banks are yet to offer RuPay credit cards. In terms of acceptance, RuPay cards are now accepted at all outlets that accept other major credit cards like Visa and Mastercard across India. RuPay has also partnered with Discover, JCB, etc. to expand international acceptance. However, its acceptance and international reach may differ from those of Visa and Mastercard.
Visa cards are offered by almost every major bank in India including top private banks. Visa claims to have the largest merchant network spanning 200+ countries and territories. It is accepted on a vast scale worldwide, including at all major establishments in India.
Like Visa, Mastercard is also offered by leading banks. It has a strong global presence and is accepted at millions of merchants, hotels, and websites worldwide. In India too, it enjoys wide coverage like Visa.
RuPay credit cards are more economical, with exciting joining offers and rewards on UPI payments. Interest rates are on par with Visa and Mastercard. RuPay enjoys wide acceptance across India and is rapidly expanding its global footprint through partnerships. Exclusive benefits like airport lounge access make RuPay more beneficial for Indian users. Integration of UPI payments on RuPay cards provides an additional, convenient digital payment option.
One of the key differentiators of RuPay Credit Cards is their integration with UPI. Eligible RuPay Credit Cards can be linked to supported UPI apps, allowing you to use your credit limit for payments at participating merchants.
QR-based payments: You can scan a supported UPI QR code and pay directly using your linked RuPay Credit Card.
Everyday convenience: This is particularly useful for retail purchases, dining, grocery shopping and other merchant transactions.
Secure authentication: UPI transactions require authentication, adding an additional layer of security.
Rewards: Eligible IDFC FIRST Bank RuPay Credit Cards may offer rewards on qualifying UPI transactions, subject to card-specific terms.
The payment network itself is only one factor when comparing credit cards. You should also evaluate the fees and charges applicable to the specific card.
Factor |
Aspect to Consider |
Joining/annual fee |
Applicable fee and waiver conditions |
Forex markup |
Impact on international transactions |
UPI charges |
Applicable charges and transaction exclusions |
Processing fees |
Charges for services such as EMI conversion or cash withdrawal |
Reward redemption |
Review redemption rules, fees and applicable limits |
The actual charges depend on the credit card issuer and card variant, and not only on whether the card operates on RuPay, Visa or Mastercard.
Security is important regardless of the payment network you choose. RuPay Credit Cards linked to UPI combine card-based security with UPI authentication.
You should:
Never share your UPI PIN, OTP, CVV or card credentials.
Verify the merchant name and transaction amount before authorising payments.
Monitor card statements regularly for unauthorised transactions.
Report suspicious transactions promptly to your card issuer.
Visa and Mastercard cards also use established security and authentication mechanisms for card transactions. Therefore, your payment habits and the security features offered by the issuer are important considerations alongside the network.
The right payment network depends on your spending pattern, preferred payment method and travel requirements.
Choose RuPay if you frequently use UPI and want convenient QR-based merchant payments.
Choose Visa if broad international acceptance is a priority for your travel and spending needs.
Choose Mastercard if you value its extensive global merchant network and associated card benefits.
Compare the specific card, rather than choosing solely by network. Evaluate fees, rewards, UPI compatibility, lounge access, forex charges, insurance and other benefits.
For IDFC FIRST Bank customers, comparing the benefits of the underlying credit card along with the available RuPay, Visa or Mastercard variant can help you select an option aligned with your financial and lifestyle needs.
While Visa and Mastercard currently have an edge over RuPay cards in terms of premium features and global acceptance, RuPay cards are fast catching up by adding new benefits tailored for Indian customers. UPI on RuPay has made it more accessible as well. As NPCI expands RuPay’s network and ties up with more banks, the value proposition of RuPay cards for Indian consumers will become even more compelling.
IDFC FIRST Bank offers RuPay credit cards as an add-on to Visa cards with just a ₹199 fee. This unique feature allows customers to enjoy the benefits of both networks. The easy UPI transactions using add-on activation benefit on lifetime free credit cards make it a great choice for customers.
Apply for the unique IDFC FIRST Digital RuPay Credit Card today and get rewarded on all your spends and pay using UPI. This card offers a host of benefits tailored to the needs of Indian customers, making it a great choice for anyone looking to maximize the value of their credit card.
The better network depends on your spending and usage. RuPay is particularly useful for domestic payments and UPI transactions, while Visa and Mastercard offer wider international acceptance. Compare rewards, fees, travel benefits, and acceptance before choosing.
Yes, eligible RuPay credit cards can be linked to supported UPI apps for payments at participating merchants. This lets you use your credit limit for UPI transactions, subject to the issuer’s terms.
Yes, RuPay cards can be used internationally where supported. However, acceptance is not as extensive as Visa or Mastercard, making the latter more suitable for frequent overseas usage.
Not necessarily. Fees are determined largely by the card issuer and card variant rather than only the payment network. Compare joining fees, annual fees, forex charges, cash withdrawal charges, and other costs.
A direct network conversion may not always be available. You may need to request a RuPay variant or apply for an eligible RuPay card offered by your bank. Check with your issuer for available options.
Visa or Mastercard may be preferable because of their broad global acceptance. Also compare forex charges, travel rewards, and airport lounge benefits.
All three networks support security features, but the exact details depend on the issuer and transaction type. UPI-enabled RuPay payments use authentication such as a UPI PIN, while cards may also use OTPs, transaction alerts, and other security controls.
The contents of this article/infographic/picture/video are meant solely for information purposes. The contents are generic in nature and for informational purposes only. It is not a substitute for specific advice in your own circumstances. The information is subject to updation, completion, revision, verification and amendment and the same may change materially. The information is not intended for distribution or use by any person in any jurisdiction where such distribution or use would be contrary to law or regulation or would subject IDFC FIRST Bank or its affiliates to any licensing or registration requirements. IDFC FIRST Bank shall not be responsible for any direct/indirect loss or liability incurred by the reader for taking any financial decisions based on the contents and information mentioned. Please consult your financial advisor before making any financial decision.
The features, benefits and offers mentioned in the article are applicable as on the day of publication of this blog and is subject to change without notice. The contents herein are also subject to other product specific terms and conditions and any third party terms and conditions, as applicable. Please refer our website www.idfcfirst.bank.in for latest updates.


Earn IndiGo BluChips | Redeem on IndiGo flights | Power of Dual cards | 1.49% Forex Mark Up

Lounge access, 10X Reward, ₹4000 cashback, Zero Forex, Spa, Golf access

1% Forex, 10X rewards, Lounge, Spa, Golf and Movies

Buy-1-Get-1 Movie ticket offers, airport lounge access, 1.5% forex markup, railway lounge visits






Earn IndiGo BluChips | Redeem on IndiGo flights | Power of Dual cards | 1.49% Forex Mark Up
Know MoreLounge access, 10X Reward, ₹4000 cashback, Zero Forex, Spa, Golf access
Know MoreBuy-1-Get-1 Movie ticket offers, airport lounge access, 1.5% forex markup, railway lounge visits
Know MoreLounge access, 10X Reward, ₹4000 cashback, Zero Forex, Spa, Golf access
Know MoreFuel Card, 5% fuel savings, 2.5% Grocery & Utility Savings, 0 interest cash
Know MoreZero Annual Fee, Complimentary airport lounge access, Low forex mark-up at 1.99%, Buy-1-Get-1 Movie ticket offers
Know More