



Login to Internet banking
A brand-new experience - smarter, faster, and secured
You gain a dedicated partner committed to helping you reach your full potential and achieve new heights
Know More
BRAVO (Auto Sweep)
Convert the idle funds in your current account into a fixed deposit with the BRAVO feature.
Know More
Zero Forex Markup Current Account
Maximise your savings and boost profitability with our Zero Forex Markup current accounts
Know More



Enjoy Zero Forex on all IDFC FIRST Bank Credit Cards
Save more on all international spends
Know More
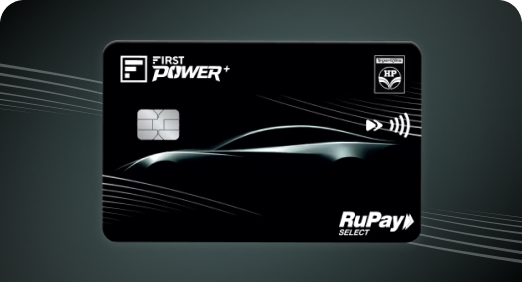
A Card that Powers your Savings & Lifestyle
IDFC FIRST Bank HPCL Credit Card

Most Searched
Earn up to 7% interest on your Savings Account
Open Account Now
Download our app
Get instant help for all your queries in one place
Unlock features, exclusively available
only on the IDFC FIRST Bank app
Trusted by 1.2+ million Indians.
4.8

4.8

Tools & Calculators
Privilege Program


Tools & Calculators

Unlock features, exclusively available
only on the IDFC FIRST Bank app
 Once your residential status changes, your existing savings account becomes invalid, requiring re-designation to an NRO account to stay FEMA and RBI compliant.
You can open an NRO account for Indian income and an NRE account for foreign earnings, with NRE interest being fully tax-free and freely repatriable.
NRI accounts can be linked to stock market investments, loans, FDs, RDs, and FCNR deposits, and IDFC FIRST Bank simplifies this shift with a seamless conversion process.
You may be moving overseas for work or higher education. With the new country comes new experiences and challenges. This changes everything in terms of how you manage your income in India. If you are moving abroad or have relocated abroad and qualify as a Non-Resident Indian (NRI), you are required to redesignate your existing savings account to an NRO Account. Read ahead to learn about the changes you can expect and the right preparation to comply with the RBI and FEMA regulations.
Once you qualify as an NRI, your existing savings accounts and bank accounts are no longer active. As per the Foreign Exchange Management Act (FEMA) and RBI regulations, you are required to re-designate these accounts to NRO Account to reflect your NRI status. Implementing this change ensures your foreign and Indian income, deposits, investments and other transactions are recognised as per regulatory compliance.
You will have to either close or convert your resident savings account to open an NRO account. For this, you will need to prove your updated status through overseas address, residence permit, Passport, and other eligible KYC documents. You cannot manage money in India until you re-designate your bank accounts.
After becoming an NRI, you can convert savings account to NRO account and additionally open types of NRI accounts and deposits as per requirement. Read ahead to learn the features of each account type:
A Non-Resident Ordinary or NRO savings account helps you manage your Indian income, such as rent, dividends, interest earnings, pension, etc. The funds in this account are maintained in Indian rupees and the interest earned on them is taxable in India. You can repatriate a portion of funds, i.e., up to USD 1 million in a financial year, to your overseas account.
As you work and make investments abroad, you may want an account in India to maintain your foreign income. This is where an Non-Resident External or NRE account helps. It converts the deposits you make in foreign currency into Indian rupees for easy management. You can freely repatriate the principal and interest earnings whenever you want. Also, the interest earnings are free from taxation.
Once you set up your NRI account, you can proceed to link them with eligible financial services like:
You can invest in mutual funds, stocks, government schemes, and other eligible securities through NRI trading and demat accounts. IDFC FIRST Bank ensures quick onboarding for these accounts to reduce the hassle of keeping your investments active.
You can apply for loan options like an NRI home loan with differential rules for application and repayment with your newly attained status.
You can open an NRI fixed deposit and recurring deposit accounts to earn risk-free and assured interest on your savings by linking your NRI accounts.
Unlike NRO and NRE bank accounts, FCNR Account (Foreign Currency Non-Resident) is a fixed deposit account. It lets you park foreign income in the original currency. Most banks, like IDFC FIRST Bank, accept major currencies like USD, British Pound, Euro, etc. As there is no conversion, you are protected from exchange rate fluctuations, and the funds are tax-free and freely repatriable.
Taking the crucial steps as discussed above helps you stay financially secure in a foreign country. It ensures you are regulatorily compliant. Converting your resident accounts to NRI bank accounts is a fairly simple process.. IDFC FIRST Bank offers a seamless Resident to NRO Account Conversion process. Make sure you provide accurate and updated KYC documents to fast-track the process.
You need to convert your resident savings account to an NRO account or close it as per RBI and FEMA regulations.
An NRO account manages Indian income, while an NRE account manages foreign income and offers tax-free interest and free repatriation.
NRIs can open NRE, NRO, FCNR, fixed deposit and recurring deposit accounts based on their requirements.
The features, benefits and offers mentioned in the article are applicable as on the day of publication of this blog and is subject to change without notice. The contents herein are also subject to other product specific terms and conditions and any third party terms and conditions, as applicable. Please refer our website www.idfcfirst.bank.in for latest updates.