



Login to Internet banking
A brand-new experience - smarter, faster, and secured
You gain a dedicated partner committed to helping you reach your full potential and achieve new heights
Know More
BRAVO (Auto Sweep)
Convert the idle funds in your current account into a fixed deposit with the BRAVO feature.
Know More
Zero Forex Markup Current Account
Maximise your savings and boost profitability with our Zero Forex Markup current accounts
Know More



Enjoy Zero Forex on all IDFC FIRST Bank Credit Cards
Save more on all international spends
Know More
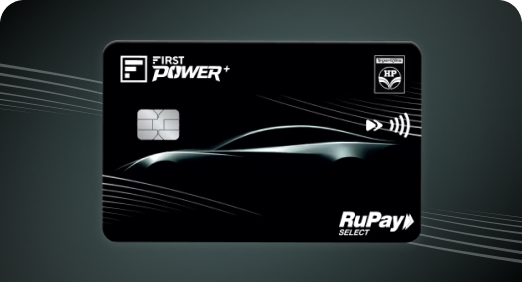
A Card that Powers your Savings & Lifestyle
IDFC FIRST Bank HPCL Credit Card

Most Searched
Earn up to 7% interest on your Savings Account
Open Account Now
Download our app
Get instant help for all your queries in one place
Unlock features, exclusively available
only on the IDFC FIRST Bank app
Trusted by 1.2+ million Indians.
4.8

4.8

Tools & Calculators
Privilege Program


Tools & Calculators

Unlock features, exclusively available
only on the IDFC FIRST Bank app
 The best NRE account in India helps to receive your overseas salary, as it keeps your funds fully repatriable, tax-efficient in India, and compliant with FEMA regulations.
Choosing the best bank for an NRE account in India helps you avoid common mistakes such as incorrect account usage while simplifying transfers, documentation, and the process for opening an NRI account.
With IDFC FIRST Bank NRI Banking Services, you get a strong contender for the best NRE account in India, offering smooth onboarding, clear compliance support, and easy global access to your funds.
You are working abroad, earning an overseas salary. However, under the Foreign Exchange Management Act (FEMA), once your status shifts to a non-resident, your existing resident savings accounts must be redesignated to NRO accounts or closed. So, where should your income be routed to stay compliant?
To do this legally and efficiently, you need a non-resident external (NRE) account. The best NRE account in India can be the primary gateway for your foreign earnings, ensuring that every Indian Rupee you remit is compliant, and accessible.
Let us take a closer look at why choosing the best NRE account in India is often considered the right way to manage your overseas salary.
Before committing to any account, you need to know the differences between NRI savings accounts, as they can affect your tax liability, repatriation rights, and regulatory compliance.
It is denominated in Indian Rupees and is specifically meant for overseas salary remitted to India. The interest earned on funds in this account is entirely tax-free in India. Additionally, the principal amount and interest are repatriable, which means that you can transfer funds abroad without any compliance issues.
This account, by contrast, is designed for income earned within India or from Indian sources, such as rental income, dividends, or a pension. Moreover, repatriation of funds from an NRO account is restricted to USD 1 million per financial year after paying all applicable taxes.
In short, to receive your overseas salary, you need the best NRE account in India.
When your overseas salary is credited to the best NRE account in India, you’re not just following rules; you’re:
Unlike NRO accounts, which cap annual repatriation at USD 1 million, NRE accounts permit unlimited repatriation of both principal and interest. This means if you’ve accumulated savings over several years and decide to relocate or invest abroad, you can transfer the entire amount.
The best bank for an NRE account in India will facilitate this repatriation through digital channels. It will allow you to initiate transfers without visiting a branch or submitting physical documentation. This efficiency is particularly valuable when you’re managing finances across time zones and continents.
Interest accrued on your NRE account is exempt from Indian income tax. This exemption applies regardless of the quantum of interest earned, making it a genuine tax advantage for NRIs with substantial balances.
Managing an overseas salary across borders can seem straightforward, but even small missteps can lead to compliance risks or restricted access to your funds. Here are the mistakes NRIs most commonly make and how you can avoid them.
Crediting foreign income into a resident account can create compliance issues. An NRE account is specifically meant for such earnings. Choosing the best NRE account in India helps you manage funds correctly while retaining repatriation and tax benefits.
Errors like mixing domestic and foreign income, outdated KYC details, or incomplete documentation can lead to delays or penalties.
To avoid these problems, structure your finances properly from the start. Opting for the best NRE account in India simplifies compliance, reduces tax concerns, and keeps your cross-border finances organised.
Securing your financial future requires more than just earning well; it requires banking smart. For managing an overseas salary, IDFC FIRST Bank’s NRI Banking Services offers a seamless, structured solution. With guided, fully digital onboarding, opening an NRI savings account is simple, quick, and accessible from anywhere in the world.
Here are the features that makes NRE Savings Account from IDFC FIRST Bank one of the best options:
With zero processing fees and competitive exchange rates, transferring your overseas salary into India becomes cost-effective and hassle-free. This is an important feature of the best NRE account in India.
You can access your account anytime through a highly rated Mobile Banking App. It enables safe and convenient banking from anywhere in the world.
Enjoy unrestricted repatriation of funds, making it easier to move money across borders when needed.
Banking needs do not stop at transactions. Dedicated relationship managers at IDFC FIRST Bank and their tailored assistance strengthen its position as the best NRE account in India for NRIs seeking guided, reliable banking.
Selecting the best NRE account in India with IDFC FIRST Bank’s NRI Banking Services ensures that your earnings are received tax-efficiently, remain fully repatriable, and stay compliant with FEMA regulations at every step.
Ready to simplify your overseas salary management? Open the best NRE account in India with IDFC FIRST Bank today and experience banking designed specifically for your needs as an NRI.
There are no prescribed limits on the amount of overseas salary you can remit to an NRE account under FEMA regulations.
An NRE Savings Account can be opened by:
Non-Resident Indians (NRIs)
Persons of Indian Origin (PIOs)
Overseas Citizens of India (OCIs)
Seafarers employed on international vessels
Oil rig personnel working on offshore international projects
With IDFC FIRST Bank, you can apply for an NRI Savings Account online while abroad or visit a branch to open one when in India.
The features, benefits and offers mentioned in the article are applicable as on the day of publication of this blog and is subject to change without notice. The contents herein are also subject to other product specific terms and conditions and any third party terms and conditions, as applicable. Please refer our website www.idfcfirst.bank.in for latest updates.