



Login to Internet banking
A brand-new experience - smarter, faster, and secured
You gain a dedicated partner committed to helping you reach your full potential and achieve new heights
Know More
BRAVO (Auto Sweep)
Convert the idle funds in your current account into a fixed deposit with the BRAVO feature.
Know More
Zero Forex Markup Current Account
Maximise your savings and boost profitability with our Zero Forex Markup current accounts
Know More



Enjoy Zero Forex on all IDFC FIRST Bank Credit Cards
Save more on all international spends
Know More
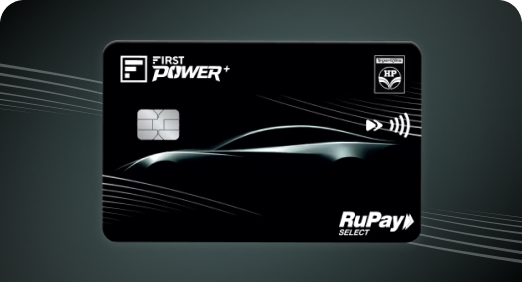
A Card that Powers your Savings & Lifestyle
IDFC FIRST Bank HPCL Credit Card

Most Searched
Earn up to 7% interest on your Savings Account
Open Account Now
Download our app
Get instant help for all your queries in one place
Unlock features, exclusively available
only on the IDFC FIRST Bank app
Trusted by 1.2+ million Indians.
4.8

4.8

Tools & Calculators
Privilege Program


Tools & Calculators

Unlock features, exclusively available
only on the IDFC FIRST Bank app
 Managing money during a PhD in the USA isn’t just about budgeting, but about handling finances across two countries without friction.
Choosing the right NRI account (NRE or NRO) ensures smooth handling of foreign income and money earned in India.
Digital NRI banking is crucial for students abroad, offering 24/7 account access, fast transfers, UPI-linked convenience, and easy account monitoring from anywhere.
IDFC FIRST Bank’s digital-first setup and competitive interest rates make cross-border transfers simple and help you track and manage your money from anywhere.
Starting your PhD in the USA is exciting, but managing money across two countries is rarely simple. Between tuition payments, living expenses, scholarships or stipends, and occasional support from home, your finances get split between India and the US pretty quickly. This is why choosing the right banking setup matters as much as choosing the right university.
Most students focus on what the requirements are for a PhD in the USA: SOPs, research fit, recommendation letters, test scores, but forget a major practical requirement once they secure an admission: smooth, safe, and flexible banking on both sides of the world.
Let’s understand how to pick the right NRI banking structure to make your international financial life easy from day one.
A PhD in the USA is typically funded, but that doesn’t mean money is easy to come by. You’ll be juggling two financial worlds: day-to-day expenses in the US and commitments back home in India. Your stipend may be steady, but rent, utilities, insurance, and travel costs can quickly eat into it.
Meanwhile, you may still have money activity in India, such as rent from a property ordividends.
Trying to manage this using a standard savings account in India won’t work. As per the prevailing FEMA regulations, you are considered as an NRI if: you are residing overseas for more than 182 days in one Financial Year (April-March); or you have demonstrated an intent with supported documents to go abroad or reside outside of India for an uncertain period.
That’s when your NRI banking setup becomes essential to handle:
Indian banks offer two key NRI account options for students:
Account type |
Purpose |
Best for |
NRE (Non-Resident External) |
Hold foreign incomes in INR |
Stipends, scholarships, and research assistant earnings transferred to India |
NRO (Non-Resident Ordinary) |
Manage income earned in India |
Rent, dividends |
Let’s break them down simply.
If you’re earning abroad, whether through a stipend, a funded assistantship, or a research fellowship, an NRE Account becomes extremely useful.
Why students prefer NRE accounts:
If you have any financial activity in India while studying abroad, the NRO account handles it smoothly.
Ideal uses of an NRO account:
Interest earned in India is taxable, and repatriation is applicable with limits (up to USD 1 million/year).
If you have income from both the US and India, use both NRE and NRO accounts.
Being in the US means you need banking that works without depending on branch visits. A good NRI account should offer:
A smooth digital experience saves hours—time you’d rather spend writing papers, meeting supervisors, or catching sleep.
As a student abroad, you don’t want complicated banking. You want reliability, clarity, and convenience. That’s where IDFC FIRST Bank fits well:
Your priority in the US will always be research, academics, and settling into a new life. But having the right banking setup can dramatically reduce the stress of cross-border finances. Choosing the right NRE or NRO account ensures your money flows stay organised and easy to manage. With IDFC FIRST Bank’s digital-first approach, attractive interest rates, and hassle-free account management, handling your finances during your PHD in the USA becomes simple, safe, and fully under your control.
An NRE account lets you hold and manage foreign income, such as stipends or scholarships, in India. NRE Account is denominated in Indian Rupees. The funds are fully repatriable, and the interest is tax-free under current rules, making it ideal for students abroad.
Yes. IDFC FIRST Bank supports digital onboarding, dedicated Relationship Managers, unlimited ATM withdrawals in India, monthly interest credits that help compound wealth, and zero processing fees on remittances. Thus, students can manage money across countries with ease.
Yes, but the rules differ for each account. Funds in an NRE account are fully repatriable, meaning you can transfer them back to the USA without restrictions. You can get repatriations up to USD 1 million per year for NRO accounts (taxes and documentation applicable). Choosing the right account helps you maintain flexibility when moving funds across countries.
Continuing to use a regular resident savings account after your status changes to NRI can lead to non-compliance with FEMA and RBI regulations. Banks may require you to redesignate your account to an NRO account. To avoid penalties or disruptions in transactions, it is advisable to update your account status and switch to the appropriate NRI account as soon as your residency status changes.
The features, benefits and offers mentioned in the article are applicable as on the day of publication of this blog and is subject to change without notice. The contents herein are also subject to other product specific terms and conditions and any third party terms and conditions, as applicable. Please refer our website www.idfcfirst.bank.in for latest updates.