



Login to Internet banking
A brand-new experience - smarter, faster, and secured
You gain a dedicated partner committed to helping you reach your full potential and achieve new heights
Know More
BRAVO (Auto Sweep)
Convert the idle funds in your current account into a fixed deposit with the BRAVO feature.
Know More
Zero Forex Markup Current Account
Maximise your savings and boost profitability with our Zero Forex Markup current accounts
Know More



Enjoy Zero Forex on all IDFC FIRST Bank Credit Cards
Save more on all international spends
Know More
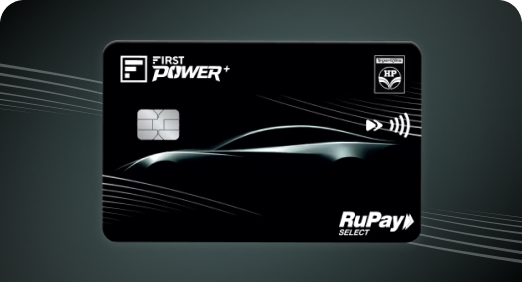
A Card that Powers your Savings & Lifestyle
IDFC FIRST Bank HPCL Credit Card

Most Searched
Earn up to 7% interest on your Savings Account
Open Account Now
Download our app
Get instant help for all your queries in one place
Unlock features, exclusively available
only on the IDFC FIRST Bank app
Trusted by 1.2+ million Indians.
4.8

4.8

Tools & Calculators
Privilege Program


Tools & Calculators

Unlock features, exclusively available
only on the IDFC FIRST Bank app
 Once you move to the USA, your residential status changes, and under RBI guidelines, you must convert your existing bank account to stay compliant. This is one of the key things to know before moving to the USA.
Continuing to use a resident Indian bank account as an NRI can lead to penalties as per FEMA guidelines, so choosing the best NRI account for India early helps you avoid disruptions and manage both Indian and foreign income efficiently.
IDFC FIRST Bank NRI Banking services enable seamless conversion of your resident account to an NRI account, fully digital account opening, and dedicated NRI support as per FEMA regulations, making it a practical option for the best NRI account for India.
Securing an H-1B or L-1 visa is no small feat. One of your first priorities as an NRI should be to set up an NRI account, as operating your regular Indian bank account is no longer compliant..
Once your residential status changes, leaving your account on autopilot while living abroad is a regulatory mismatch with the Reserve Bank of India (RBI) and the Foreign Exchange Management Act (FEMA) regulations.
To ensure your hard-earned money remains accessible, you need to identify the best NRI account for India before you fly out.
The moment you leave India or plan to leave India with the intention of taking up employment or residence abroad for an indefinite period, you are classified as an NRI under FEMA.
According to RBI guidelines, once you become an NRI, you are no longer permitted to maintain a regular resident savings account. Continuing to operate one for receiving salary credits, making transfers, or simply leaving it active, even if unintentionally, shall attract penalties as per FEMA guidelines. You must convert your resident savings account to NRO Account or close it to make way for the best NRI account for India.
The ideal timeline for managing your transition to an Indian bank account is before you relocate. While you can technically convert your account after entering the USA, doing so while you are still in India makes the process easier. You will need to provide your bank with:
Starting early ensures that when your first US paycheck arrives, you already have the best NRI account for India ready to receive your remittances.
Both are forms of Indian bank accounts designed for NRIs, but they serve distinct purposes.
A Non-Resident External (NRE) account is where you park money earned abroad. It is held in Indian rupees but funded through foreign currency. The principal and interest are freely repatriable. This means you can move the money back to the USA without restriction. Interest earned is also exempt from Indian income tax as per current Indian tax laws.
A Non-Resident Ordinary (NRO) account supports income originating in India, such as rental income, dividends, pensions. Unlike an NRE account, repatriation from an NRO account is subject to limits and tax deductions at source as per RBI guidelines.
Most NRIs need both. You can convert your existing resident savings account to an NRO account and open a fresh NRE account for saving your foreign earnings in INR. Balancing both accounts keeps your US earnings and Indian income distinct. What you truly need is a banking partner that offers the best NRI account for India with a seamless dual-account interface.
Navigating RBI guidelines can feel daunting when you are also trying to settle into a new country. IDFC FIRST Bank NRI Banking Services offers a structured, digital-first solution tailored for H-1B and L-1 visa holders. If you are an existing Resident Savings Account holder of IDFC FIRST Bank, they have streamlined the conversion process to ensure your move to the USA doesn't cause a financial disconnect at home. Alternatively, new customers can also seamless start their NRI banking relationship with IDFC FRIST Ban through their Digital Account Opening process.
With IDFC FIRST Bank, the focus is on removing the friction from Indian banking. Their platform provides a guided path for compliance, ensuring that every form you sign aligns with current FEMA and RBI regulations. For a professional moving to the USA, this level of structured support is what makes their offering the best NRI account for India.
When you are living thousands of miles away, you need a bank that feels like it’s right next door. With IDFC FIRST Bank, the best NRI account for India is not just a place to store money but a well-structured system designed for control, clarity, and peace of mind. Its NRI Banking are built around what you actually need when relocating:
However, what makes it the best NRI account for India is the following features:
One of the key things to know before moving to the USA is how easily you can manage your finances in India from abroad. With IDFC FIRST Bank, you get a fully digital setup that lets you open, access, and operate your account without visiting a branch.
Handling finances internationally requires strong safeguards. The best NRI account for India offers secure online access, allowing you to conduct transactions with confidence while protecting your financial information at every step.
Transferring funds between India and the USA should be straightforward. With repatriation facilities in line with RBI guidelines and FEMA regulations, you can remit funds abroad with clarity and without unnecessary delays.
As you adjust to a new country, having access to dedicated NRI servicing ensures you receive timely assistance, helping you stay compliant and manage your financial responsibilities smoothly.
Choosing the best NRI account for India with IDFC FIRST Bank NRI Banking Services before or soon after your move helps you stay compliant, avoid penalties, and manage your Indian finances smoothly while settling in the USA.
Switch to the best NRI account for India today and experience seamless global banking!
Yes, you can hold an NRI account jointly with a resident Indian (typically on a “former or survivor” basis).
Yes. While certain incomes (like interest on NRE accounts) may be tax-free in India, they could still be taxable in the USA based on your tax residency. It is advisable to consult a tax professional familiar with cross-border taxation.
The features, benefits and offers mentioned in the article are applicable as on the day of publication of this blog and is subject to change without notice. The contents herein are also subject to other product specific terms and conditions and any third party terms and conditions, as applicable. Please refer our website www.idfcfirst.bank.in for latest updates.