



Login to Internet banking
A brand-new experience - smarter, faster, and secured
You gain a dedicated partner committed to helping you reach your full potential and achieve new heights
Know More
BRAVO (Auto Sweep)
Convert the idle funds in your current account into a fixed deposit with the BRAVO feature.
Know More
Zero Forex Markup Current Account
Maximise your savings and boost profitability with our Zero Forex Markup current accounts
Know More



Enjoy Zero Forex on all IDFC FIRST Bank Credit Cards
Save more on all international spends
Know More
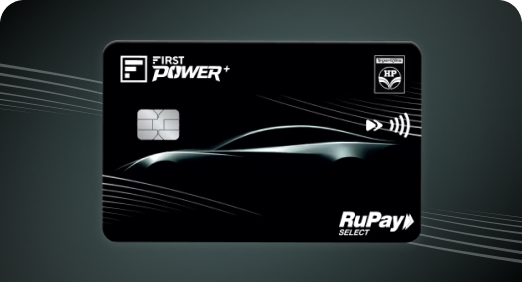
A Card that Powers your Savings & Lifestyle
IDFC FIRST Bank HPCL Credit Card

Most Searched
Earn up to 7% interest on your Savings Account
Open Account Now
Download our app
Get instant help for all your queries in one place
Unlock features, exclusively available
only on the IDFC FIRST Bank app
Trusted by 1.2+ million Indians.
4.8

4.8

Tools & Calculators
Privilege Program


Tools & Calculators

Unlock features, exclusively available
only on the IDFC FIRST Bank app
 Becoming an NRI requires converting your resident savings account under FEMA and RBI rules, making an NRI savings account a compliance necessity, not just an option.
It separates foreign and Indian income through NRE and NRO accounts, eases cross-border transactions, and connects to investments like FDs, mutual funds, and FCNR deposits.
IDFC FIRST Bank offers quick account opening, easy repatriation, tax-free NRE interest, competitive rates, and joint account flexibility for managing money abroad.
If you’re residing overseas but still wish to manage your finances in India, your regular savings account won’t cut it anymore. As per the FEMA and RBI guidelines, you are required to either convert your resident savings account into an NRI account or close the resident savings account. Besides meeting the regulatory requirements, this shift offers a host of benefits that make your financial life easier. As the NRI savings account is tailored for your specific needs, it includes various specialised features. Read ahead to explore them.
Once you move abroad, your finances need to adapt to the new regulations. Part of this is ceasing the use of your regular savings account and opening NRI savings accounts. Here’s how it makes a difference:
Continued use of your regular savings account isn’t allowed under the FEMI guidelines once your residential status changes. Hence, converting to an NRI account becomes a part of the compliance. Doing so avoids disruptions in your banking activities.
An NRI account helps you maintain your foreign income and the income originating in India in NRE and NRO accounts, respectively. Both the accounts are denominated in Indian Rupees (INR). This helps organise them better, and the tax and repatriation rules apply distinctly .
Sending money to India or accessing funds from abroad also becomes straightforward. With dedicated channels accessible through your NRI banking app, you can transfer money without complications.
Beyond regular banking, you can also link your NRI accounts to investment avenues like NRI FDs, mutual funds, direct equities, etc., to grow your savings. You may also directly deposit funds in foreign currency in an FCNR deposit to earn interest without the exchange rate risk.
Owing to the digital banking tools, you can manage your NRI accounts, track transactions, and handle day-to-day banking activity from anywhere, as per your convenience.
An NRI savings account makes managing money across borders and making important financial decisions easier owing to these benefits:
Opening an NRI account involves a streamlined process with online applications that enables opening of an account from your overseas country of residence.
From tracking transactions to managing payments, everything is managed in a single place. All you need is a banking app to access banking services. This brings structure to your financial responsibilities in India and your resident country.
The money you deposit is easy to transfer back to your overseas bank account. There are no restrictions on NRE and FCNR deposit accounts. An NRO account offers a similar convenience with a limit of USD 1 million for a financial year.
You get clear tax advantages for foreign income management The interest earned on your NRE Savings Account is completely tax-free in India, as long as you maintain your NRI status under FEMA regulations. This tax exemption, along with free repatriation, makes the NRE account a highly efficient option for NRIs to grow and manage their money in India.
Many banks and NBFCs offer competitive interest rates on NRI accounts. This means your parked funds grow steadily. Also, some banks credit interest on a monthly basis, which lets you earn interest on interest, resulting in higher returns.
You can use many NRI banking services at low or even zero cost. Whether it’s ATM transactions, cheque collection, demand draft, or cash deposits, most banks offer these facilities at minimal charges, making banking more affordable.
You can add another NRI or a resident family as a joint account holder (Resident holders can be added on a ‘former’ or ‘survivor’ basis). You may also appoint a Power of Attorney (PoA) to manage funds locally on your behalf if needed.
As your financial responsibilities continue across borders after becoming an NRI, having the right structure in place becomes essential. This is where NRI accounts help. You can manage your foreign income through an NRE and an FCNR deposit account. Meanwhile, an NRO account is apt for your Indian income. As your plans evolve, the base created with these accounts makes it easier to explore investments, loans, and insurance options in India.
No, it must be converted to an NRI account or closed after moving abroad.
NRE accounts manage foreign income, while NRO accounts manage income earned in India.
It offers easier cross-border banking, repatriation, tax benefits, digital management, and investment access.
The features, benefits and offers mentioned in the article are applicable as on the day of publication of this blog and is subject to change without notice. The contents herein are also subject to other product specific terms and conditions and any third party terms and conditions, as applicable. Please refer our website www.idfcfirst.bank.in for latest updates.