



Login to Internet banking
A brand-new experience - smarter, faster, and secured
You gain a dedicated partner committed to helping you reach your full potential and achieve new heights
Know More
BRAVO (Auto Sweep)
Convert the idle funds in your current account into a fixed deposit with the BRAVO feature.
Know More
Zero Forex Markup Current Account
Maximise your savings and boost profitability with our Zero Forex Markup current accounts
Know More


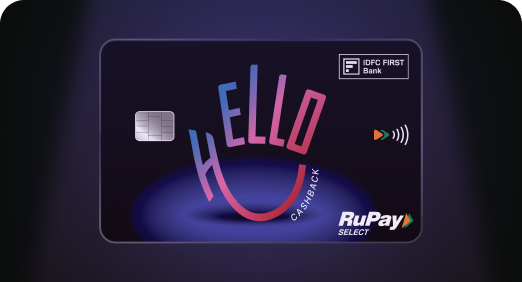

Enjoy Zero Forex on all IDFC FIRST Bank Credit Cards
Save more on all international spends
Know More
A Card that Powers your Savings & Lifestyle
IDFC FIRST Bank HPCL Credit Card

Most Searched
Earn up to 7% interest on your Savings Account
Open Account Now
Download our app
Get instant help for all your queries in one place
Unlock features, exclusively available
only on the IDFC FIRST Bank app
Trusted by 1.2+ million Indians.
4.8

4.8

Tools & Calculators
Privilege Program


Tools & Calculators

Unlock features, exclusively available
only on the IDFC FIRST Bank app
Credit Card
 A ₹20,000 salary doesn't lock you out of credit card options. Most banks set entry-level eligibility near this mark, and FD-backed cards skip income checks entirely.
At this income level, even a small joining or annual fee can outweigh the rewards earned, so lifetime-free and fee-waiver cards tied to spend thresholds hold more real value.
The right card depends on how you spend. FIRST Millennia suits those earning near ₹25,000 a month, while those earning below that can start with Quantum+, FIRST EARN, or Hello Cashback, all FD-backed cards needing no income proof.
A monthly income of ₹20,000 does not shut you out of the credit card market. Several banks issue cards to first-time earners at this level, and FD-backed options skip the income check altogether. If you are comparing a credit card for 20,000 salary, the real work lies in matching the fee structure and reward categories to how you spend. Here is how to find the best option for your income level.
Most banks ask for income proof, such as salary slips or an ITR, when you apply for an entry-level card. FD-backed cards do not require income documents at all. If you do not have the documents a bank asks for, an FD-backed card is one of the best credit cards for 20k salary earners, and your fixed deposit continues to earn interest while you use it. Once your income or CIBIL score improves, upgrading to a regular card gets easier.
If you earn ₹20,000 a month, even a small yearly fee could seem like an extra cost. So, a card with a low or zero annual fee lets you get more value from the card without adding much to your regular expenses.
Cards with a lower income threshold, or FD-backed cards that skip income proof, open the door faster. This is the route most people searching for a credit card for 20,000 salary end up choosing.
Dining, groceries, UPI and online shopping account for most of what a ₹20,000 earner spends monthly. A card that rewards these categories delivers value you will actually use.
Picking the best credit card for 20k salary comes down to two paths: a regular credit card if your income meets the eligibility criteria, or an FD-backed card if it does not. IDFC FIRST Bank offers both options.
A lifetime free card with no joining or annual fee. It requires a minimum annual income of ₹3 lakh, close to ₹25,000 a month, so it suits earners at or just above the ₹20,000 mark. Cardholders get up to 10X reward points on dining, travel and select online spends, 3X on UPI transactions, four complimentary railway lounge visits a quarter and 25% off on movie tickets.
An FD-backed, lifetime free card that needs no income proof or CIBIL, and your credit limit is 100% of the FD value. You earn up to 2% cashback on online spends, 1% on UPI scan-and-pay via the IDFC FIRST Bank app, and 0.5% on categories like utility bills, rent and insurance.
An FD-backed, UPI-first card built around a smaller fixed deposit of just ₹5,000, one of the more accessible entry points into a credit card. The joining fee is currently ₹0 under a limited-period offer, and the annual fee is ₹499, waived once your spends cross ₹1 lakh in a year. It offers 1% cashback on UPI spends through the IDFC FIRST Bank app and 0.5% on other UPI apps and select bill categories.
Backed by a fixed deposit of ₹10,000, this card suits online shoppers who want a higher cashback rate. The joining fee is currently zero under an introductory offer, and the annual fee is ₹1,000, reversed once yearly spends cross ₹2 lakh. It offers up to 5% cashback on online spends, plus 1% cashback on UPI payments and an additional 1% on flight and hotel bookings via the app.
Card |
Joining fee |
Annual fee |
Best for |
FIRST Millennia |
None |
None |
Earners nearing ₹25,000 a month |
Quantum+ |
None |
None |
Cashback without income proof |
FIRST EARN |
₹0 (limited-period offer) |
₹499+GST, waived on ₹1 lakh annual spends |
Lowest FD entry point |
Hello Cashback |
₹0 (introductory offer) |
₹1,000+GST, waived on ₹2 lakh annual spends |
Frequent online shoppers |
Clear the bill in full: Carrying a balance forward attracts interest that can outweigh any cashback or rewards earned that month.
Watch your utilisation: Keep spends under 30% of your credit limit, since high usage can lower your CIBIL score even when you pay on time.
Never miss a due date: A single late payment stays on your credit report and can affect future loan or card approvals.
Master one card first: Build a steady repayment record before adding a second card, so lenders see consistency rather than a scattered history.
A ₹20,000 salary is a workable starting point for a credit card, not a limitation. Lifetime free and FD-backed options mean you do not need a high income or a CIBIL to get one and using that first card well sets you up for better cards later. Choose the card that matches your spending pattern and start building your credit profile today.
No, your FD keeps earning interest as usual and simply sits as collateral against your credit limit.
Joining and annual fees are waived, but late payment fees, cash withdrawal fees and interest on unpaid balances still apply if you miss a due date.
If your income is closer to ₹25,000 a month, the FIRST Millennia Credit Card gives you the strongest reward rate for a lifetime free card. If your income sits below that, Quantum+, FIRST EARN or Hello Cashback let you get started against a fixed deposit instead, with Hello Cashback suiting online shoppers who want a higher cashback rate.
The contents of this article/infographic/picture/video are meant solely for information purposes. The contents are generic in nature and for informational purposes only. It is not a substitute for specific advice in your own circumstances. The information is subject to updation, completion, revision, verification and amendment and the same may change materially. The information is not intended for distribution or use by any person in any jurisdiction where such distribution or use would be contrary to law or regulation or would subject IDFC FIRST Bank or its affiliates to any licensing or registration requirements. IDFC FIRST Bank shall not be responsible for any direct/indirect loss or liability incurred by the reader for taking any financial decisions based on the contents and information mentioned. Please consult your financial advisor before making any financial decision.
The features, benefits and offers mentioned in the article are applicable as on the day of publication of this blog and is subject to change without notice. The contents herein are also subject to other product specific terms and conditions and any third party terms and conditions, as applicable. Please refer our website www.idfcfirst.bank.in for latest updates.


Earn IndiGo BluChips | Redeem on IndiGo flights | Power of Dual cards | 1.49% Forex Mark Up

Lounge access, 10X Reward, ₹4000 cashback, Zero Forex, Spa, Golf access

1% Forex, 10X rewards, Lounge, Spa, Golf and Movies

Buy-1-Get-1 Movie ticket offers, airport lounge access, 1.5% forex markup, railway lounge visits






Earn IndiGo BluChips | Redeem on IndiGo flights | Power of Dual cards | 1.49% Forex Mark Up
Know MoreLounge access, 10X Reward, ₹4000 cashback, Zero Forex, Spa, Golf access
Know MoreBuy-1-Get-1 Movie ticket offers, airport lounge access, 1.5% forex markup, railway lounge visits
Know MoreLounge access, 10X Reward, ₹4000 cashback, Zero Forex, Spa, Golf access
Know MoreFuel Card, 5% fuel savings, 2.5% Grocery & Utility Savings, 0 interest cash
Know MoreZero Annual Fee, Complimentary airport lounge access, Low forex mark-up at 1.99%, Buy-1-Get-1 Movie ticket offers
Know More