



Login to Internet banking
A brand-new experience - smarter, faster, and secured
You gain a dedicated partner committed to helping you reach your full potential and achieve new heights
Know More
BRAVO (Auto Sweep)
Convert the idle funds in your current account into a fixed deposit with the BRAVO feature.
Know More
Zero Forex Markup Current Account
Maximise your savings and boost profitability with our Zero Forex Markup current accounts
Know More


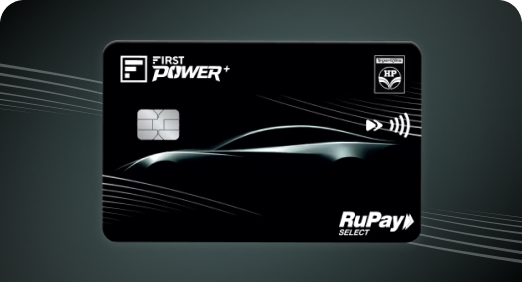
A Card that Powers your Savings & Lifestyle
IDFC FIRST Bank HPCL Credit Card

Most Searched
Earn up to 7% interest on your Savings Account
Open Account Now
Download our app
Get instant help for all your queries in one place
Unlock features, exclusively available
only on the IDFC FIRST Bank app
Trusted by 1.2+ million Indians.
4.8

4.8

Tools & Calculators
Privilege Program


Tools & Calculators

Unlock features, exclusively available
only on the IDFC FIRST Bank app
Savings Account
 Build an emergency fund covering three to six months of essential expenses before the festive season.
Set a separate festival budget for clothes, food and gifts so you do not dip into your emergency savings.
Automate monthly transfers to a separate emergency fund and top it up with bonuses or leftover festival budgets.
Onam brings new clothes, festive feasts and family gatherings, and festival spending can add up fast. Between Onakkodi outfits, Onasadya groceries and gifts for the family, it's easy to dip into money you had set aside for the unexpected.
Building a safety net before the festive season begins means you can enjoy the celebrations without worrying about a sudden medical bill or car repair later. A high yield savings account for emergency fund works well here, since your money stays easy to reach while it still grows through interest.
This blog looks at how much to set aside, how to manage festival costs and how to keep the two goals apart.
In emergency fund planning, a common starting point is three to six months of essential costs, such as rent, groceries, utilities and loan instalments. India's official household spending survey (2023 to 24, Ministry of Statistics) puts the average urban spend at ₹6,996 per person a month.
Say your household has four members spending around this average, that works out to close to ₹28,000 a month. Six months of this comes to roughly ₹1.68 lakh. Your own number will change with your family size, city and monthly bills, but this gives you a grounded starting range.
A little planning keeps Onam spending in check and away from your safety net. A 2025 survey found 37% of urban households plan to spend ₹20,000 or more this festive season.
Set a budget: Decide a fixed limit for clothes, food and gifts, and hold to it.
Save in advance: Set a small amount aside each month before Onam instead of scrambling for funds all at once.
Track spending: Check your bank app against your budget as the festival nears.
Protect your fund: Pay using UPI or debit card instead of dipping into money required for daily expenses or your emergency savings fund.
This fund works best alongside your festival budget:
Automate transfers: Move a fixed sum to your fund each month before festival shopping starts.
Keep it separate: Use a different account so festival spending never touches this money.
Choose a high yield account: A high yield savings account for emergency fund, like the IDFC FIRST Bank Savings Account, pays up to 7% p.a. monthly, allows unlimited withdrawals, and keeps deposits insured up to ₹5 lakh under DICGC.
Top it up: Add any Onam bonus or leftover budget into the fund after celebrations.
Onam carries its own rhythm of spending, from family travel to new clothes and festive meals, often helped along by bonuses and money sent home by relatives working abroad. None of this needs to come at the cost of emergency fund planning.
The aim isn't to cut back on celebrations, but to plan around them. Keep your emergency fund untouched and let your festival budget carry the season's costs. This way, Onam stays a time of celebration and doesn't stress your finances, while your safety net keeps growing in the background, ready for whatever comes once the festivities end.
Keeping the two apart pays off through the year:
Clear money picture: You always know how much you can spend on festivities and how much stays untouched for emergencies.
No debt reliance: You're less likely to reach for a loan or credit card if urgent costs come up after Onam.
Steady growth: Your emergency savings fund keeps earning interest through the year instead of being spent down every season or sitting idle.
Guilt-free celebrations: You get to enjoy Onam fully, knowing your safety net is intact.
Onam is worth celebrating fully, and emergency fund planning makes that easier. Work out a realistic amount to set aside, keep it in a separate account away from your festival budget, and let that budget cover the celebrations. With the two goals kept apart, you get to enjoy this Onam and stay ready for whatever comes next.
A common starting point is three to six months of essential costs such as rent, groceries, utilities and loan instalments.
Keep it in a separate high-interest savings account where the money stays accessible while earning interest. The IDFC FIRST Bank Savings Account offers up to 7% p.a. interest on progressive balances, credited monthly into your savings account, making your savings work harder for you, sooner.
Move a fixed sum to your emergency fund each month, keep it separate from festival spending and add bonuses or leftover budgets after celebrations.
The contents of this article/infographic/picture/video are meant solely for information purposes. The contents are generic in nature and for informational purposes only. It is not a substitute for specific advice in your own circumstances. The information is subject to updation, completion, revision, verification and amendment and the same may change materially. The information is not intended for distribution or use by any person in any jurisdiction where such distribution or use would be contrary to law or regulation or would subject IDFC FIRST Bank or its affiliates to any licensing or registration requirements. IDFC FIRST Bank shall not be responsible for any direct/indirect loss or liability incurred by the reader for taking any financial decisions based on the contents and information mentioned. Please consult your financial advisor before making any financial decision.
The features, benefits and offers mentioned in the article are applicable as on the day of publication of this blog and is subject to change without notice. The contents herein are also subject to other product specific terms and conditions and any third party terms and conditions, as applicable. Please refer our website www.idfcfirst.bank.in for latest updates.


You will earn