



Login to Internet banking
A brand-new experience - smarter, faster, and secured
You gain a dedicated partner committed to helping you reach your full potential and achieve new heights
Know More
BRAVO (Auto Sweep)
Convert the idle funds in your current account into a fixed deposit with the BRAVO feature.
Know More
Zero Forex Markup Current Account
Maximise your savings and boost profitability with our Zero Forex Markup current accounts
Know More


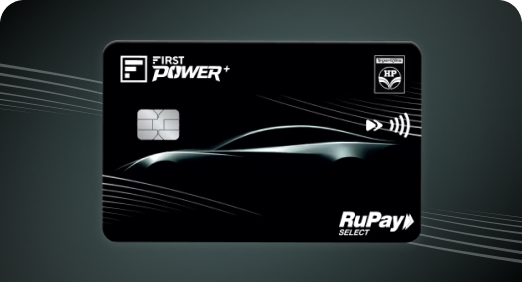
A Card that Powers your Savings & Lifestyle
IDFC FIRST Bank HPCL Credit Card

Most Searched
Earn up to 7% interest on your Savings Account
Open Account Now
Download our app
Get instant help for all your queries in one place
Unlock features, exclusively available
only on the IDFC FIRST Bank app
Trusted by 1.2+ million Indians.
4.8

4.8

Tools & Calculators
Privilege Program


Tools & Calculators

Unlock features, exclusively available
only on the IDFC FIRST Bank app
Savings Account
 Retail inflation touched 4.38% in June 2026, with food prices rising faster than the headline number.
Idle money in a low-interest account can lose real value once inflation runs ahead of the interest earned.
Progressive slabs and monthly credit help a savings account keep pace with rising costs.
Inflation in India has been climbing through 2026, and everyday essentials are getting costlier faster than the headline figures suggest. This raises a big question: is your savings account return keeping pace?
For that to happen, the account needs to earn more than the rate of inflation, otherwise, idle money is quietly losing value even as the balance keeps looking the same. A high interest savings account in India is one of the most practical ways to protect that value, without giving up easy access to funds.
India's Consumer Price Index (CPI) inflation rose to 4.38% in June 2026, its highest reading under the new CPI series, with food inflation at 5.32% meaning grocery bills are rising faster than overall prices. This follows a steady climb from 2.75% in January to 3.93% in May showing pressure on budgets has been building for months.
This shows up as a higher grocery bill, a costlier cooking gas refill, or a fuel top-up that stretches the budget further. Income growth does not move as quickly as these costs, which is why the return earned on savings starts to matter more.
The first step in knowing how to beat inflation with savings is understanding why idle money loses value:
Real returns turn negative: If inflation runs higher than the account's rate, buying power falls even though the passbook number stays the same
Everyday costs rise faster: Food and fuel inflation often outpace headline CPI
Compounding frequency matters: Quarterly interest credit compounds slower than monthly credit
Opportunity cost adds up: A rate that barely covers inflation misses out on a better return elsewhere
Bank |
Savings account interest rate (p.a.) |
Interest crediting frequency |
IDFC FIRST Bank |
Up to 7% |
Monthly |
State Bank of India |
2.50% |
Quarterly |
HDFC Bank |
2.50% |
Quarterly |
ICICI Bank |
2.50% |
Quarterly |
Axis Bank |
2.50% |
Quarterly |
Rates are as of August 2026 and change from time to time; check each bank's official page for the latest figures. With inflation at 4.38%, most savings accounts in the table above are earning below what it takes to grow real value. IDFC FIRST Bank's rate clears that mark, backed by monthly interest credit making it a strong high interest bank account in India for anyone comparing options.
Progressive interest slabs: A rate that rises with balance held rewards higher savings
Monthly interest credit: Daily interest calculation, credited monthly, compounds sooner
Low minimum balance: Gives flexibility to hold funds without added charges
Premium debit card: Premium benefits help offset some of the pinch from rising prices
These are the features that decide whether a savings account actually protects your money from inflation or just holds it.
With inflation above 4% and food prices rising faster, a savings account's return has a direct bearing on how much savings are worth in real terms. Comparing rates, crediting frequency, and features is a practical answer for those asking how to beat inflation with savings kept in a bank account.
IDFC FIRST Bank's savings account offers up to 7% p.a. on a progressive slab structure, with interest calculated daily and credited monthly, along with a reward-packed debit card. For anyone comparing a high interest savings account in India, these features help idle money work harder while staying just as accessible as any other savings account.
When inflation rises, prices for everyday goods rise faster. If a savings account's rate is lower than inflation, the real value of that money falls over time, even though the balance looks the same.
Look at the interest rate structure, crediting frequency, minimum balance requirement, and what rewards your debit card offers.
This varies by bank. Some banks credit interest every quarter, while banks like IDFC FIRST Bank credit it monthly. Monthly credit lets your balance earn on the added interest sooner, adding up considerably over a year.
The contents of this article/infographic/picture/video are meant solely for information purposes. The contents are generic in nature and for informational purposes only. It is not a substitute for specific advice in your own circumstances. The information is subject to updation, completion, revision, verification and amendment and the same may change materially. The information is not intended for distribution or use by any person in any jurisdiction where such distribution or use would be contrary to law or regulation or would subject IDFC FIRST Bank or its affiliates to any licensing or registration requirements. IDFC FIRST Bank shall not be responsible for any direct/indirect loss or liability incurred by the reader for taking any financial decisions based on the contents and information mentioned. Please consult your financial advisor before making any financial decision.
The features, benefits and offers mentioned in the article are applicable as on the day of publication of this blog and is subject to change without notice. The contents herein are also subject to other product specific terms and conditions and any third party terms and conditions, as applicable. Please refer our website www.idfcfirst.bank.in for latest updates.


You will earn